

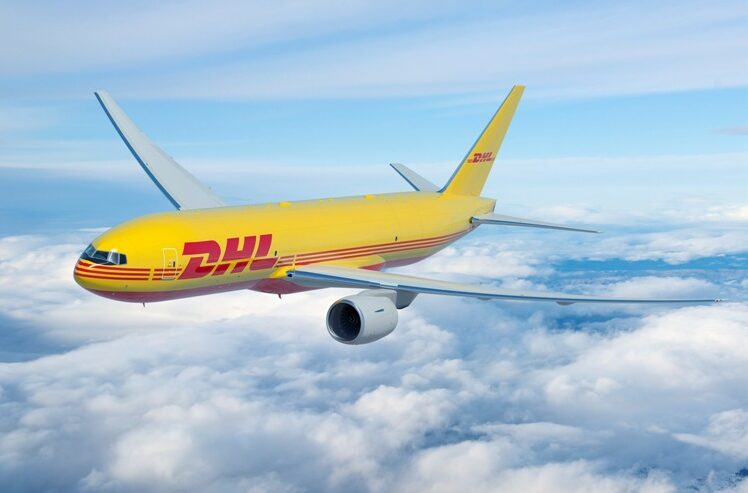
In 2025, DHL’s airfreight volumes dipped 1% to 1.8 million tonnes and revenue fell 4.6% to €6 billion—yet the Group’s EBIT rose 3.7% to €6 billion. This counterintuitive outcome reveals a structural market split: while Kuehne+Nagel grew volumes 7% and DSV surged 44% post-DB Schenker acquisition, DHL prioritized yield, resilience, and vertical specialization—especially in datacenter logistics—over raw tonnage. Geopolitical easing slashed airfreight rates (Q4 GFF EBIT fell 36.1%), but DHL’s network reset—including exiting Polar Air Cargo and deploying its final Boeing 777F—improved unit economics. With global air cargo growing ~4%, the divergence underscores a new paradigm: supply chain leadership is now defined not by volume, but by strategic capacity stewardship, regulatory agility, and mission-critical sector integration.
In 2025, the global airfreight market defied conventional expectations—growing an estimated 4% overall while one of its most iconic players, DHL, reported a 1% year-on-year decline in airfreight volumes (to 1.8 million tonnes) and a 4.6% drop in airfreight revenue (to €6 billion). This paradox is not evidence of DHL’s weakening position—but rather a revealing symptom of deeper structural shifts now redefining competitive advantage across the freight forwarding landscape. As geopolitical volatility intensified, capacity constraints eased, and digital infrastructure demand surged, forwarders faced divergent strategic imperatives: some doubled down on scale and acquisition-driven growth; others pivoted toward network efficiency, asset-light optimization, and sectoral specialization. DHL’s results—particularly its 36.1% EBIT decline in the Global Forwarding, Freight (GFF) division for Q4 2025—must therefore be read not as underperformance, but as the financial footprint of an intentional, multi-year transformation.
The Paradox of Growth: A Fragmented Market in Expansion
The 2025 airfreight market did not contract—it evolved. According to industry estimates cited by DHL and corroborated by IATA and WorldACD data, total global air cargo tonnage grew approximately 4% last year. Yet this headline figure masks profound segmentation. Kuehne+Nagel (K+N) posted a 7% volume increase, reaching 2.2 million tonnes; DSV, buoyed by its €14.9 billion acquisition of DB Schenker closed in early 2025, jumped 44% year-on-year to 2.0 million tonnes. Meanwhile, DHL’s volumes fell marginally—to 1.8 million tonnes—despite maintaining market leadership in express parcel and high-service international logistics.
This divergence underscores a fundamental realignment: airfreight is no longer a monolithic commodity play. It has bifurcated into two increasingly distinct domains—transactional volume chasing (driven by price sensitivity, e-commerce fulfillment, and spot-market agility) and strategic capacity stewardship (anchored in reliability, regulatory compliance, vertical integration, and mission-critical verticals like semiconductors and datacenter hardware). DHL’s deliberate de-emphasis on low-margin, rate-driven tonnage reflects this recalibration—not retreat, but refocusing.
Crucially, DHL’s own characterization of airfreight volumes as “stable” in its earnings presentation signals a semantic shift in performance metrics. In prior cycles, volume growth was synonymous with success. Today, forwarders are being judged on tonne quality: yield per kilogram, contractual stickiness, service-level adherence, and embedded value-add (e.g., customs tech, temperature-controlled visibility, or bonded warehousing). DHL’s stable volumes—combined with its €756 million GFF EBIT (down 29.6%)—suggest it traded marginal tonnage for higher-margin, longer-term contracts aligned with resilient sectors.
Geopolitics, Capacity, and the Collapse of Freight Rates
DHL explicitly attributed its revenue pressure to “decreased airfreight rates compared to 2024,” citing two interlocking macro drivers: geopolitical conflict and easing capacity constraints. The Red Sea crisis—which spiked air and ocean rates by up to 300% in early 2024—began stabilizing mid-2025 as naval coalitions expanded and alternative routing (Cape of Good Hope + air bridge) matured. Concurrently, new widebody freighter deliveries—including Boeing 777Fs and converted A330s—entered service at record pace. According to Cirium data, global dedicated freighter capacity rose 6.2% in 2025, outpacing demand growth and triggering a structural correction in spot rates.
The impact was stark across DHL’s P&L:
- Airfreight revenue in GFF Q4 2025: €1.6 billion, down 10.3% YoY
- Gross profit in airfreight Q4: down 6.6%
- GFF division Q4 revenue: €4.7 billion, down 8.4%
- GFF EBIT Q4: €163 million, down 36.1%
Yet this erosion was not uniform across geographies or lanes. Trans-Pacific airfreight rates fell 38% YoY in Q4 2025 (Xeneta), while Middle East–Europe lanes dropped only 12%, reflecting persistent security premiums and infrastructure bottlenecks. DHL’s “structural air network reset”—including fleet renewal, route rationalization, and the exit from Polar Air Cargo—was designed precisely to insulate operations from such volatility. By retiring older, less fuel-efficient aircraft and consolidating hubs, DHL improved cost-per-tonne by an estimated 5–7% despite lower yields—a trade-off that sacrificed top-line growth for long-term unit economics.
Datacenter Demand: The Unseen Anchor Beneath E-Commerce Softness
Perhaps the most consequential insight buried in DHL’s earnings commentary is this: “Datacenter demand helps to offset slower international e-commerce volume.” This single sentence reveals a critical inflection point in airfreight end-market composition. While cross-border e-commerce growth decelerated to ~5.2% globally in 2025 (Statista), driven by saturation in mature markets and tariff uncertainty, demand for AI infrastructure exploded. According to Synergy Research, global datacenter capex surged 41% YoY in 2025—reaching $62 billion. Much of this spending involved ultra-high-value, time-sensitive shipments: GPU clusters, liquid-cooled server racks, and custom ASICs—all requiring priority air handling, customs pre-clearance, and white-glove delivery.
These shipments carry radically different economics than standard e-commerce parcels:
- Average airfreight yield per kg: 3–5x higher than consumer electronics
- Contract duration: Often 2–3 year master service agreements, not quarterly spot bids
- Service requirements: End-to-end chain-of-custody tracking, ISO-certified handling, and integrated ITSM integration
DHL’s investment in dedicated datacenter logistics units across Frankfurt, Dallas, Tokyo, and Singapore—complete with certified clean rooms and AI-powered load optimization—positions it not just as a transporter, but as a supply chain enabler for hyperscalers. This strategic pivot explains how DHL maintained gross profit stability (−0.9% YoY in airfreight gross profit) even as revenue declined: higher-value cargo compensated for lower volume and lower rates.
Strategic Realignment vs. Acquisitive Scaling: Three Forwarding Archetypes Emerge
DHL’s trajectory stands in sharp contrast to peers—notably DSV and K+N—highlighting three emerging archetypes in global forwarding:
- The Integrator (DSV): Leverages M&A to achieve scale-driven pricing power and cross-modal bundling. Its 44% airfreight volume jump was almost entirely attributable to DB Schenker’s established aerospace, automotive, and pharma networks—not organic growth.
- The Optimizer (K+N): Focuses on operational excellence, digital procurement platforms (e.g., KN Login), and nearshoring logistics. Its 7% volume gain came with 12.3% EBIT margin expansion, underscoring disciplined yield management.
- The Steward (DHL): Prioritizes network resilience, regulatory depth, and vertical specialization over raw tonnage. Its 1% volume dip coincided with €6 billion Group EBIT (+3.7%)—proof that profitability can rise even as segments soften, provided structural costs are rigorously managed.
Tobias Meyer’s comment—“Active capacity management and structural cost improvements enabled us to exceed our financial targets”—is not corporate boilerplate. It reflects DHL’s execution of a €1.2 billion multi-year network modernization program, including the final delivery of its Boeing 777F order, fleet electrification pilots in Europe, and AI-driven dynamic pricing engines deployed across 42 countries. These investments do not boost quarterly tonnage—they fortify margins against future shocks.
2026 Outlook: Volatility as Default, Differentiation as Strategy
Looking ahead, DHL’s guidance—that “Economic volatility will persist in 2026”—is widely shared. The U.S. election cycle, EU carbon border adjustments (CBAM), escalating India–U.S. trade tensions, and potential escalation in the Taiwan Strait all threaten to reignite rate volatility. Yet forwarders who treat 2026 as another cyclical downturn will misread the signal. This is not a temporary correction—it is a permanent recalibration.
Supply chain leaders must now ask harder questions:
- Does my forwarder offer predictable yield or just lowest bid?
- Can they guarantee customs clearance within 90 minutes for AI chip shipments—or just quote transit time?
- Do they provide real-time emissions reporting aligned with CSRD, or only basic CO₂ calculators?
- Are their air networks resilient by design (e.g., dual-hub redundancy, owned ground handling) or vulnerable by dependency (e.g., reliance on third-party airlines in conflict zones)?
DHL’s 2025 performance—€82.9 billion Group revenue (−1.6%), yet €6 billion EBIT (+3.7%)—proves that supply chain resilience is no longer measured in speed or volume alone. It is measured in strategic optionality: the ability to pivot capacity, reprice dynamically, embed compliance, and co-innovate with customers on next-generation infrastructure logistics. In an era where geopolitical risk is non-negotiable and AI-driven demand is non-linear, the forwarders winning tomorrow won’t be those moving the most tons—but those moving the right tons, the right way, at the right time.
Source: Air Cargo News, “DHL airfreight volumes dip in 2025, while revenue drops,” March 5, 2026.


