East Coast diesel inventories plunged to 20.3 million barrels—the lowest since March 2015—and down more than 47% since the start of 2022. Physical spot prices in New York Harbor surged to nearly $5/gallon, widening the Gulf Coast–New York spread to 60–70 cents per gallon—versus a normal few cents. Refining capacity in PADD 1 fell from 1.224 million bpd in mid-2020 to 818,000 bpd today. Colonial Pipeline allocations weakened, signaling reduced supply nominations. Love’s reported intermittent diesel outages, and the Fuel Merchants Association of New Jersey warned of localized supply shortfalls. Elevated distillate exports—averaging >1.4 million bpd over five weeks—further strained availability.
East Coast diesel inventories plummet, spot prices soar — FreightWaves
Plummeting inventories drive physical price surge
Even as diesel futures prices plummeted Thursday by 15.576 cents per gallon, one of the larger declines in the recent wild diesel market of the last three months, the market’s larger focus has been just what a small amount of diesel the U.S. East Coast has in storage.
“You’d need to bring your mop to get the oil off the tank walls,” Ernie Barsamian, president and founder of tank storage brokerage company The Tank Tiger, said of the current inventory situation.
The June contract for ultra low sulfur diesel on the CME commodity exchange fell Thursday as part of the broader sell-off of virtually all financial assets, including a decline in the Dow Jones Industrial Average that stood at more than 1,000 points most of the day. But the East Coast diesel market is almost like a world unto its own given its inventory levels. Its tight supplies are reflected in physical prices.
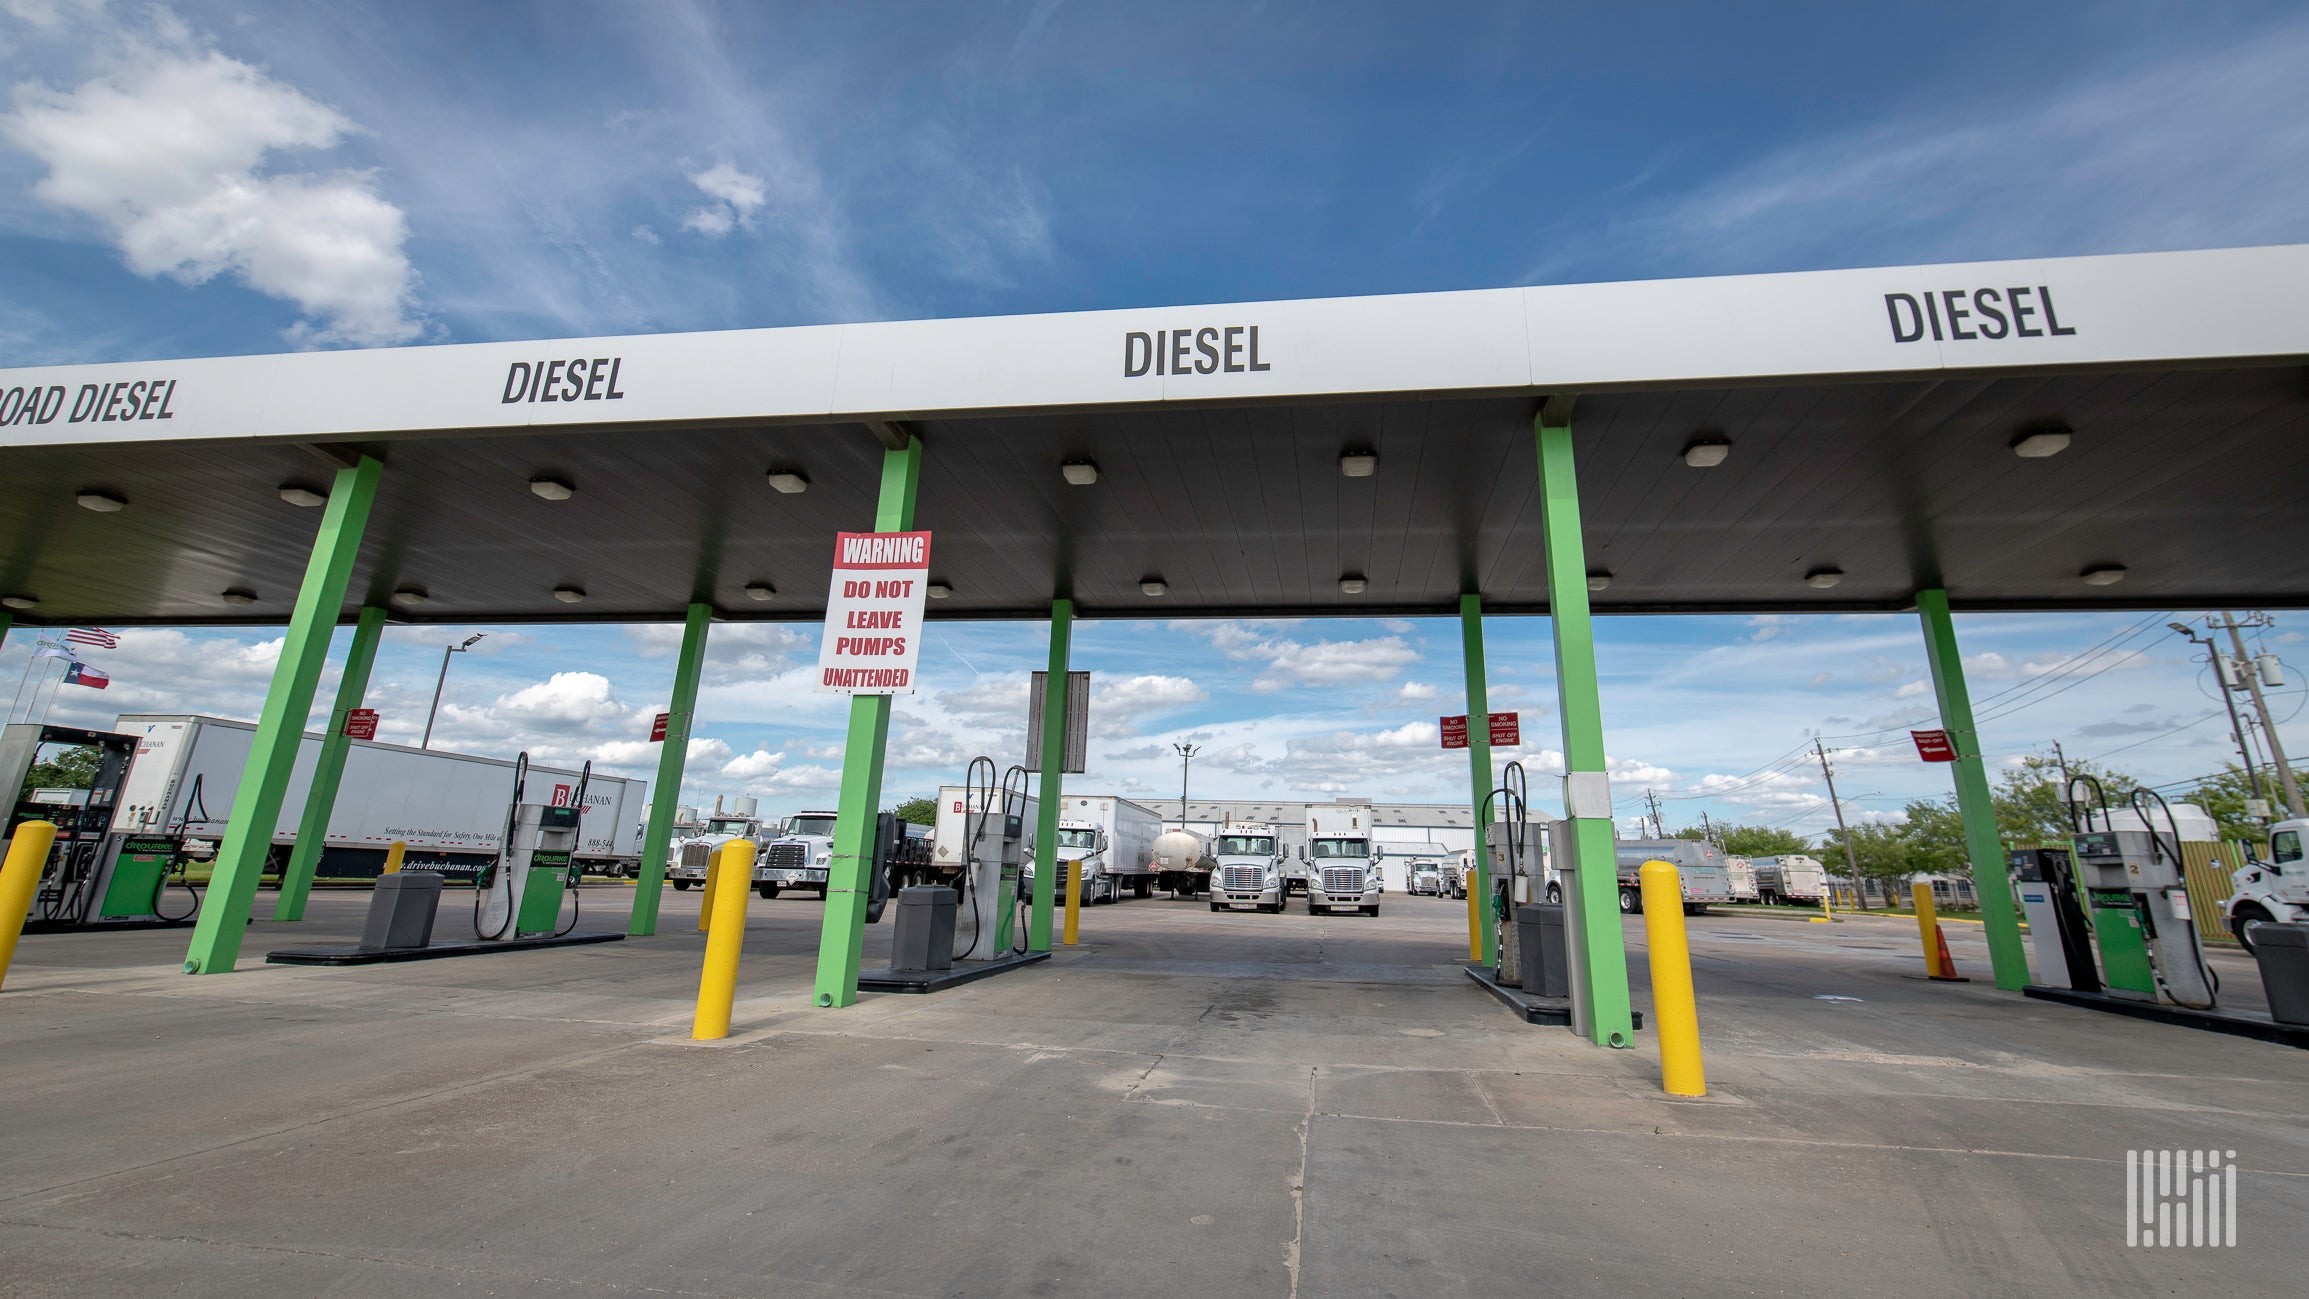
Reports of where it has hit down to the level of the pump are spotty. But a spokesman for Love’s said the company has seen “intermittent diesel outages.”
“Love’s is monitoring the fluid situation on the East Coast,” spokeswoman Caitlin Campbell said in an email to FreightWaves. “The company isn’t currently restricting purchases. Love’s will continue to use its logistics and fuel delivery companies, Musket and Gemini, to minimize impacts to customers.”
Widening Gulf Coast–New York harbor price spread
On Monday, according to price reporting agency General Index, the price of physical diesel in the Gulf Coast was just under $4.50 per gallon. The price of physical diesel in New York harbor, the delivery point of the CME ULSD contract, was just under $5 a gallon, for a spread of roughly 50 cents. In a normal market, that spread would be measured as a few cents per gallon.
On Tuesday, the New York harbor price (actual delivery point is Linden, New Jersey, on the Colonial Pipeline) was down to just over $4.83 per gallon, according to General Index. Gulf Coast prices fell slightly more, pushing the spread out to about 52 cents per gallon.
But Wednesday, as inventory statistics from the Energy Information Administration were analyzed by a stunned trading community, the Gulf Coast price rose about 2 cents per gallon, while the New York harbor price climbed anywhere from 13.9 cents to 16.4 cents per gallon, depending on the specific General Index assessment.
The end result? A Gulf Coast to New York spread in the physical market of about 60 cents to 70 cents per barrel, for a relationship that in more normal times is measured in a few cents.
On Thursday, the General Index spread was approximately 66 cents, so the big drop in the futures price did not impact the physical relationship between the Gulf Coast and New York harbor.
Futures vs. prompt physical pricing disconnect
The surge in physical diesel in New York harbor Wednesday came as the futures price for June barrels — the time stamp of the current front-month contract — rose 11.43 cents a gallon to $4.197 per gallon. If prices from last week are set aside as the result of a fierce end-of-month squeeze, the settlement Wednesday was the third highest in the history of the contract.
And yet the CME price was still roughly 80 cents less than the physical assessment that was just under $5. The difference? The futures contract is for delivery of ULSD anytime in June. The physical assessment is for barrels of ULSD delivered on the Colonial Pipeline in the 62nd cycle, which is the most prompt five-day cycle that is being scheduled.
And in the current oil market, but particularly diesel, nothing is more valuable than product a buyer can get its hands on right now. So prompt physical diesel in New York harbor is trading far more than a barrel of the same product that could be delivered just three to four weeks from now.
Record-low PADD 1 inventories and shrinking refining capacity
The tight squeeze for diesel supplies can be most clearly seen in the latest data for inventories. While diesel in the U.S. is squeezed throughout the entire country and world, there is nowhere the squeeze is being felt more than on the East Coast, known by its U.S. government description as PADD 1.
Comparison to past inventory levels can be misleading because ULSD — with less than 15 parts per million of sulfur — moved into the diesel world gradually over the last 10 to 15 years as sulfur regulations tightened. But the latest report has several eye-popping numbers:
- At 20.3 million barrels of ULSD held in PADD 1 inventory, stocks are at the lowest level since a run of recorded inventories on either side of 20 million barrels in March 2015. But back then, a brutally cold winter probably resulted in some distillate molecules being diverted to the heating oil pool rather than the diesel pool. (Similar numbers were posted in the winter of 2014, which also was a freezing few months on the U.S. East Coast, where most heating oil is consumed.)
- PADD 1 inventories are down more than 47% since the start of the year and are down by roughly half since the start of December 2021.
- The U.S. East Coast has seen several refineries close in recent years. The EIA’s operable capacity number for PADD 1 is 818,000 barrels a day. As recently as mid 2020, it was 1.224 million barrels per day.
- The Colonial Pipeline, which carries diesel, gasoline and other products from the Gulf Coast to the mid-Atlantic and Northeast states, is on allocation but at lower levels than usual, according to press reports. Demand for space on Colonial almost always exceeds supplies, and the space is then allocated. But the reports are that the allocations are less severe than usual, suggesting that supplies being nominated to move on the pipeline are falling below usual levels.
Distribution-level disruptions and export pressure
Eric DeGesoro, the executive vice president of the Fuel Merchants Association of New Jersey, said the tight supplies are a “worldwide concern.” His organization represents the middle point of the distribution between the refineries and importers of fuel and the service stations or large end-user consumers, like a trucking company.
Asked if he saw outages in the system, he cited one member who had “a little supply outage” from its supplier that was expected to be in place until Saturday morning. The member was notified of it by Thursday. But he expressed some broader caution.
“Is that foreshadowing what we might be seeing?” DeGesoro said. “That is unknown right now.”
When markets become extremely tight, such as in the wake of a hurricane and the supply outages that go along with it, fuel allocations generally favor long-term customers, such as big fleets that might have contractual arrangements with a large retailer or a wholesaler. If markets are so squeezed that they need to go on allocation, it is the independent owner-operators who usually take the brunt of that policy decision.
Another factor in tightening the market that is beginning to receive attention is the elevated level of diesel exports.
Monthly data from the EIA does report on more specific classification of exports, such as ULSD. But the weekly report just lists distillate exports, of which diesel would be the biggest part.
The weekly figure on distillate exports in the last two reports has had a rolling five-week average in excess of 1.4 million barrels per day of all distillate exports, including diesel. In the history of the export series provided by the EIA, that has only occurred 10 times in the data series that goes back to 2010. Data shows that back-to-back weeks in excess of 1.4 million barrels per day have not occurred since July 2019.
Source: FreightWaves
Compiled from international media by the SCI.AI editorial team.