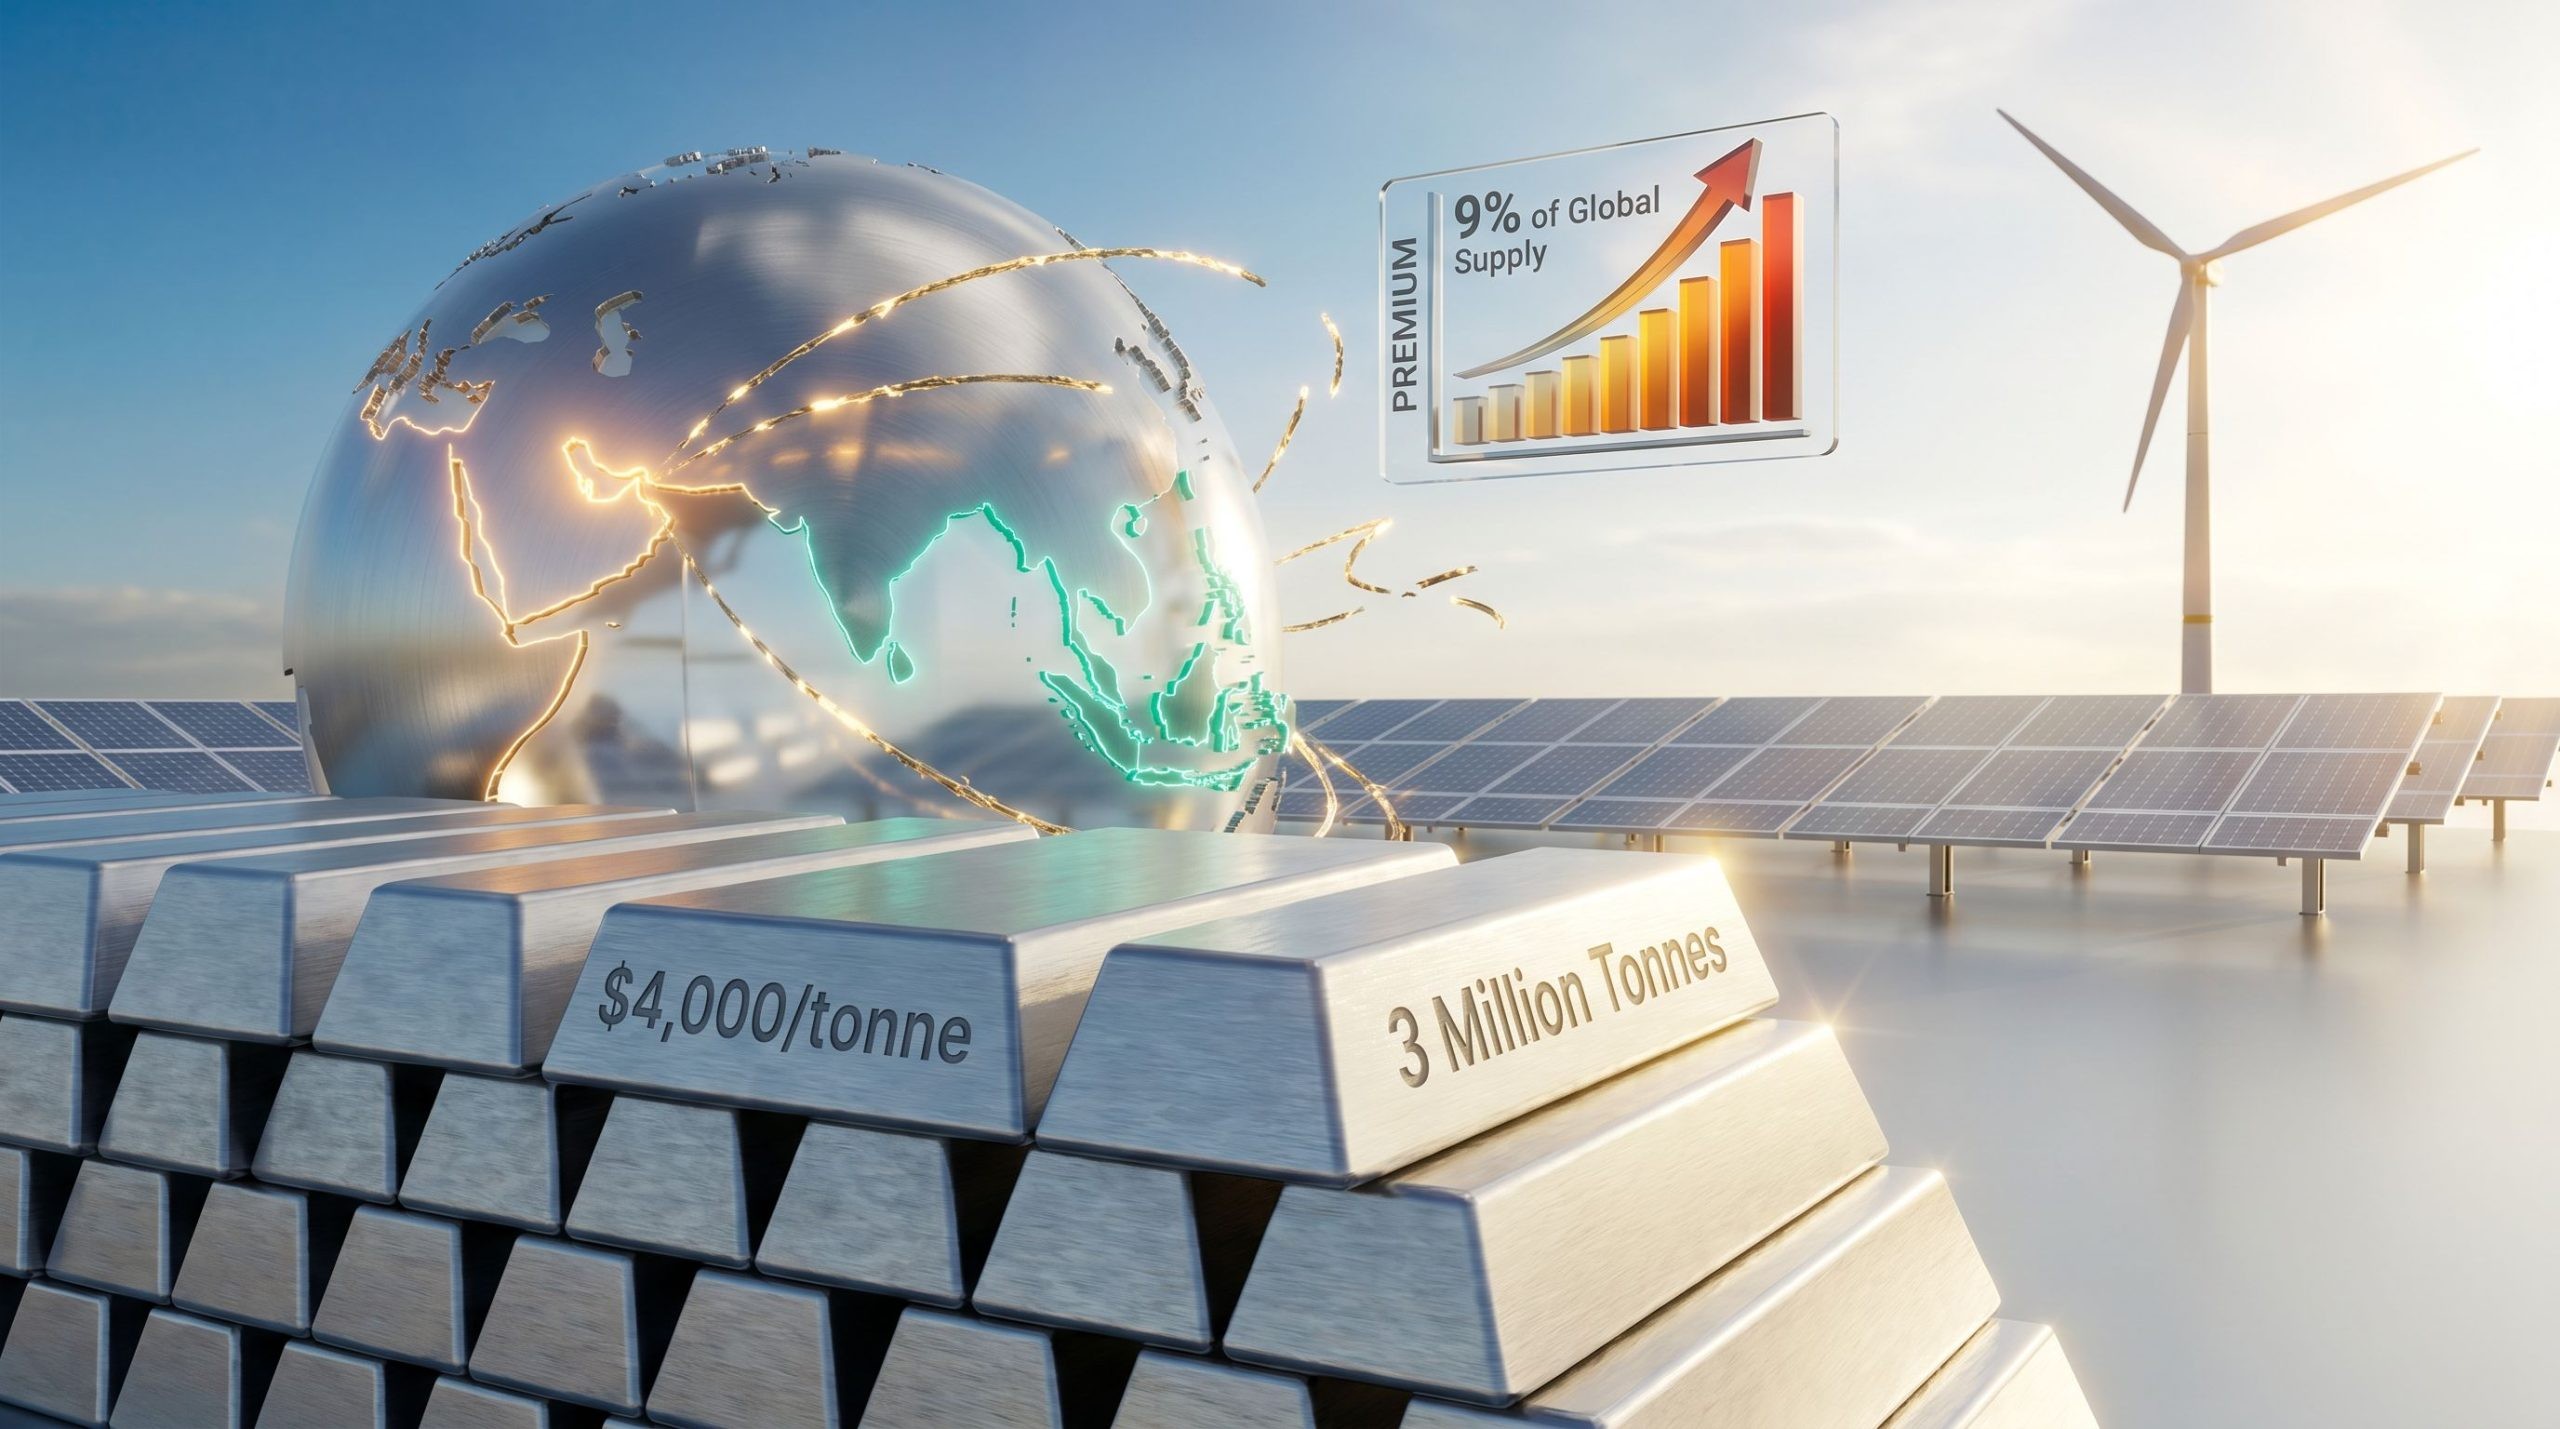
The Middle East conflict is disrupting Asia’s green aluminium supply chain, pushing all-in landed costs above $4,000/tonne in key markets. GCC smelters — responsible for 9% of global output — face constrained operations amid Strait of Hormuz shipping risks. Estimated annualised capacity losses reach 1.6 million tonnes, with total regional output at risk up to 3 million tonnes. Global supply loss projections for 2026 range from 3 to 3.5 million tonnes — roughly 5% of the 70-million-tonne annual global production. Asia’s renewable buildout — including Indonesia’s 44% by 2030 target and Vietnam’s rapid solar expansion — relies entirely on imported primary aluminium, making procurement teams acutely vulnerable.
According to discoveryalert.com.au, the ongoing Middle East conflict is disrupting Asia’s green aluminium supply chain, triggering a supply shock that has already pushed all-in landed costs above $4,000 per tonne in key Asian markets. The disruption stems from operational constraints at Gulf Cooperation Council (GCC) smelters and elevated war-risk insurance surcharges on vessels transiting conflict-adjacent waters — particularly through the Strait of Hormuz.
Aluminium’s Indispensable Role in Asia’s Clean Energy Buildout
Solar panel frames, wind turbine nacelle housings, EV battery enclosures, and high-voltage transmission cables all rely heavily on aluminium. A single megawatt of utility-scale solar capacity requires 3 to 5 tonnes of aluminium just for framing and mounting structures. With Asia planning hundreds of gigawatts of new renewable capacity over the next decade, cumulative aluminium demand embedded in those projects totals tens of millions of tonnes. Indonesia, Vietnam, and the Philippines — Southeast Asia’s three fastest-growing clean energy markets — have no meaningful domestic primary aluminium smelting capacity. Indonesia targets 44% renewable energy in its national electricity mix by 2030; Vietnam ranks among the world’s largest solar installers by deployment speed; and the Philippines is advancing grid modernisation requiring substantial aluminium conductor material.
GCC’s Structural Role in Global Aluminium Supply
The GCC collectively accounts for approximately 9% of global primary aluminium supply, with major operations in the UAE, Bahrain, and Qatar. This concentration is rooted in access to low-cost natural gas: primary aluminium smelting consumes 13 to 15 kilowatt-hours of electricity per kilogram of metal produced. Gulf producers serve as key swing exporters to both European and Asian buyers — giving them outsized influence despite their share size. Crucially, the Strait of Hormuz handles not only finished aluminium exports but also inbound shipments of bauxite and alumina needed to feed Gulf smelters — creating a dual vulnerability.
Quantified Supply Shock and Market Impact
Capacity losses at specific Gulf smelting installations are estimated at 1.6 million tonnes on an annualised basis. When direct and indirect impacts are combined, total regional output at risk may reach 3 million tonnes. Analyst projections cited across industry commentary suggest the global market could face a net supply loss of 3 to 3.5 million tonnes of aluminium output through 2026. That represents roughly 5% of global primary aluminium production, which runs at approximately 70 million tonnes per year. Inventory buffers are thin, amplifying price sensitivity. Regional delivery premiums — reflecting local supply-demand imbalances and logistics risk — have surged sharply: European aluminium premiums have hit record or near-record levels, while US Midwest premiums have tracked upward.
Practitioner Implications for Supply Chain Professionals
- Procurement teams across Jakarta, Manila, and Ho Chi Minh City now face immediate cost inflation on solar farm, wind installation, and grid upgrade capital budgets due to higher landed aluminium prices.
- Buyers relying on CIF contracts are absorbing war-risk insurance surcharges passed directly from underwriters — a dynamic cost not tied to LME base price alone.
- Supply chain mapping must now include secondary chokepoints: not just origin smelter location, but vessel routing through the Strait of Hormuz and insurance underwriting terms.
- Long-term sourcing strategies are shifting toward diversified feedstock routes and pre-positioned inventory buffers — especially for critical infrastructure projects with fixed commissioning deadlines.
“Asia’s clean energy ambitions are structurally inseparable from global aluminium supply security. Any sustained disruption to primary supply does not merely affect commodity markets. It directly inflates the capital cost of every solar farm, wind installation, and grid upgrade across the region.” — Source report
Source: discoveryalert.com.au
Compiled from international media by the SCI.AI editorial team.