

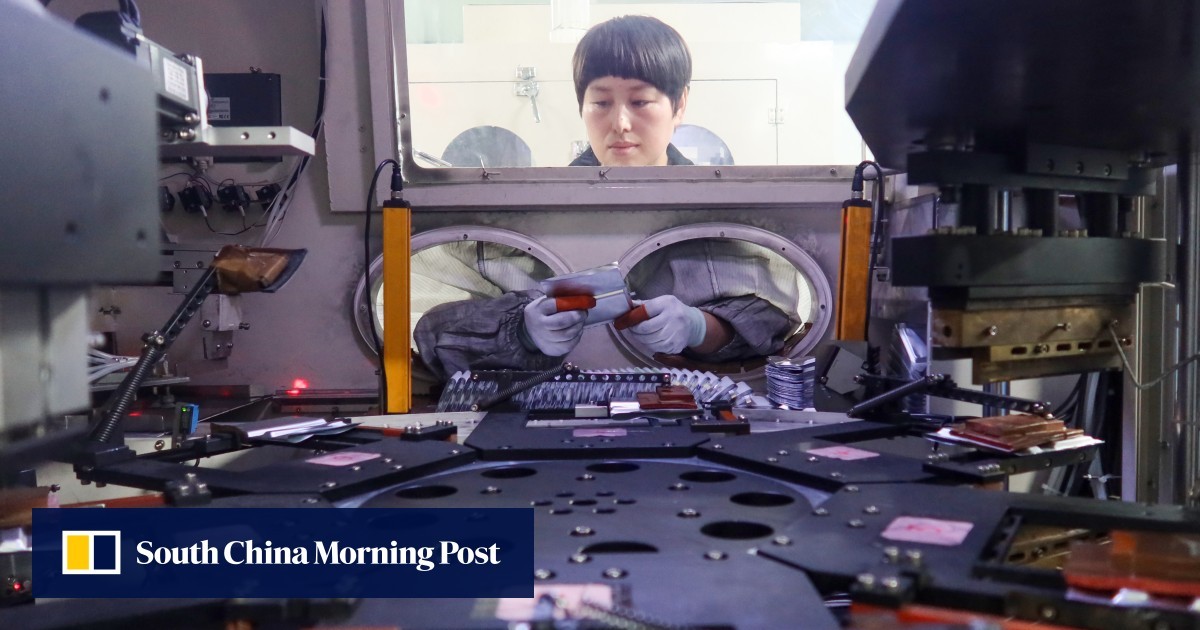
Chinese battery makers are positioned to gain from surging global energy storage demand triggered by the US-Israeli war in Iran, according to Fitch Ratings. Leading LFP battery producers hold absolute advantages in technology, cost-efficiency, and scale, with China producing over 80% of all batteries and nearly all LFP capacity. The global lithium-ion battery market exceeded $150 billion last year, growing over 20%. Production costs in the US and EU remain up to 50% higher than in China, even excluding subsidies. Supply chain professionals should anticipate stronger overseas order flows but also assess concentration risks and supplier sustainability.
According to www.scmp.com, Chinese battery cell manufacturers are poised to benefit from shifting global energy storage demand amid the US-Israeli war in Iran — even as domestic price wars, overcapacity, and thin margins pressure downstream firms.
Global Demand Surge Driven by Oil Prices and AI Infrastructure
Global demand for energy storage is expected to rise, driven by high oil prices and the rapid expansion of artificial intelligence (AI) data centres, said Wang Ying, a managing director at Fitch Ratings. At a media briefing in Beijing on Tuesday, she emphasized that China’s leading energy storage cell manufacturers hold an “overwhelming advantage globally”.
LFP Batteries: Dominance in Technology, Cost, and Scale
As an example, Wang highlighted Chinese producers of lithium iron phosphate (LFP) batteries — widely used in electric vehicles and energy storage systems — possessing “absolute” advantages in technology, cost-efficiency and industrial scale. She added:
“Consequently, it will be difficult for competitors from other countries to replace them in the short term.” — Wang Ying, Managing Director, Fitch Ratings
Market Scale and Concentration Risks
The global lithium-ion battery market expanded by more than 20 per cent to exceed US$150 billion last year, according to a February report by the International Energy Agency (IEA). That report warned of concentration risks in the global supply chain and stated that China produced more than 80 per cent of all batteries and accounted for “almost all global manufacturing capacity and the associated technical expertise” for LFP batteries.
Cost Competitiveness and Domestic Pressure
Chinese manufacturers are significantly more cost-competitive than Western counterparts: production expenses in the United States and Europe are up to 50 per cent higher, even when government support is excluded, according to the IEA report. This cost edge stems from a hyper-competitive domestic market, where lithium-ion battery producers — one of Beijing’s “new three” sources of green growth alongside photovoltaics and electric vehicles — face persistent overcapacity and cutthroat price wars.
Practitioner Implications for Supply Chain Professionals
For global supply chain professionals, this dynamic signals both opportunity and risk. On one hand, rising overseas orders for Chinese LFP cells may improve lead times and component availability for energy storage system integrators, especially in markets facing sanctions-related procurement constraints or seeking alternatives to Western-sourced batteries. On the other hand, the extreme cost pressure within China’s battery sector raises questions about long-term supplier viability, quality consistency, and contractual flexibility — particularly as buyers increasingly negotiate volume-based pricing amid volatile raw material costs. Moreover, the IEA’s warning about supply chain concentration underscores the need for dual-sourcing strategies and deeper due diligence on technical transfer, IP ownership, and local after-sales support capabilities when onboarding new Chinese battery suppliers.
Source: South China Morning Post
Compiled from international media by the SCI.AI editorial team.


