

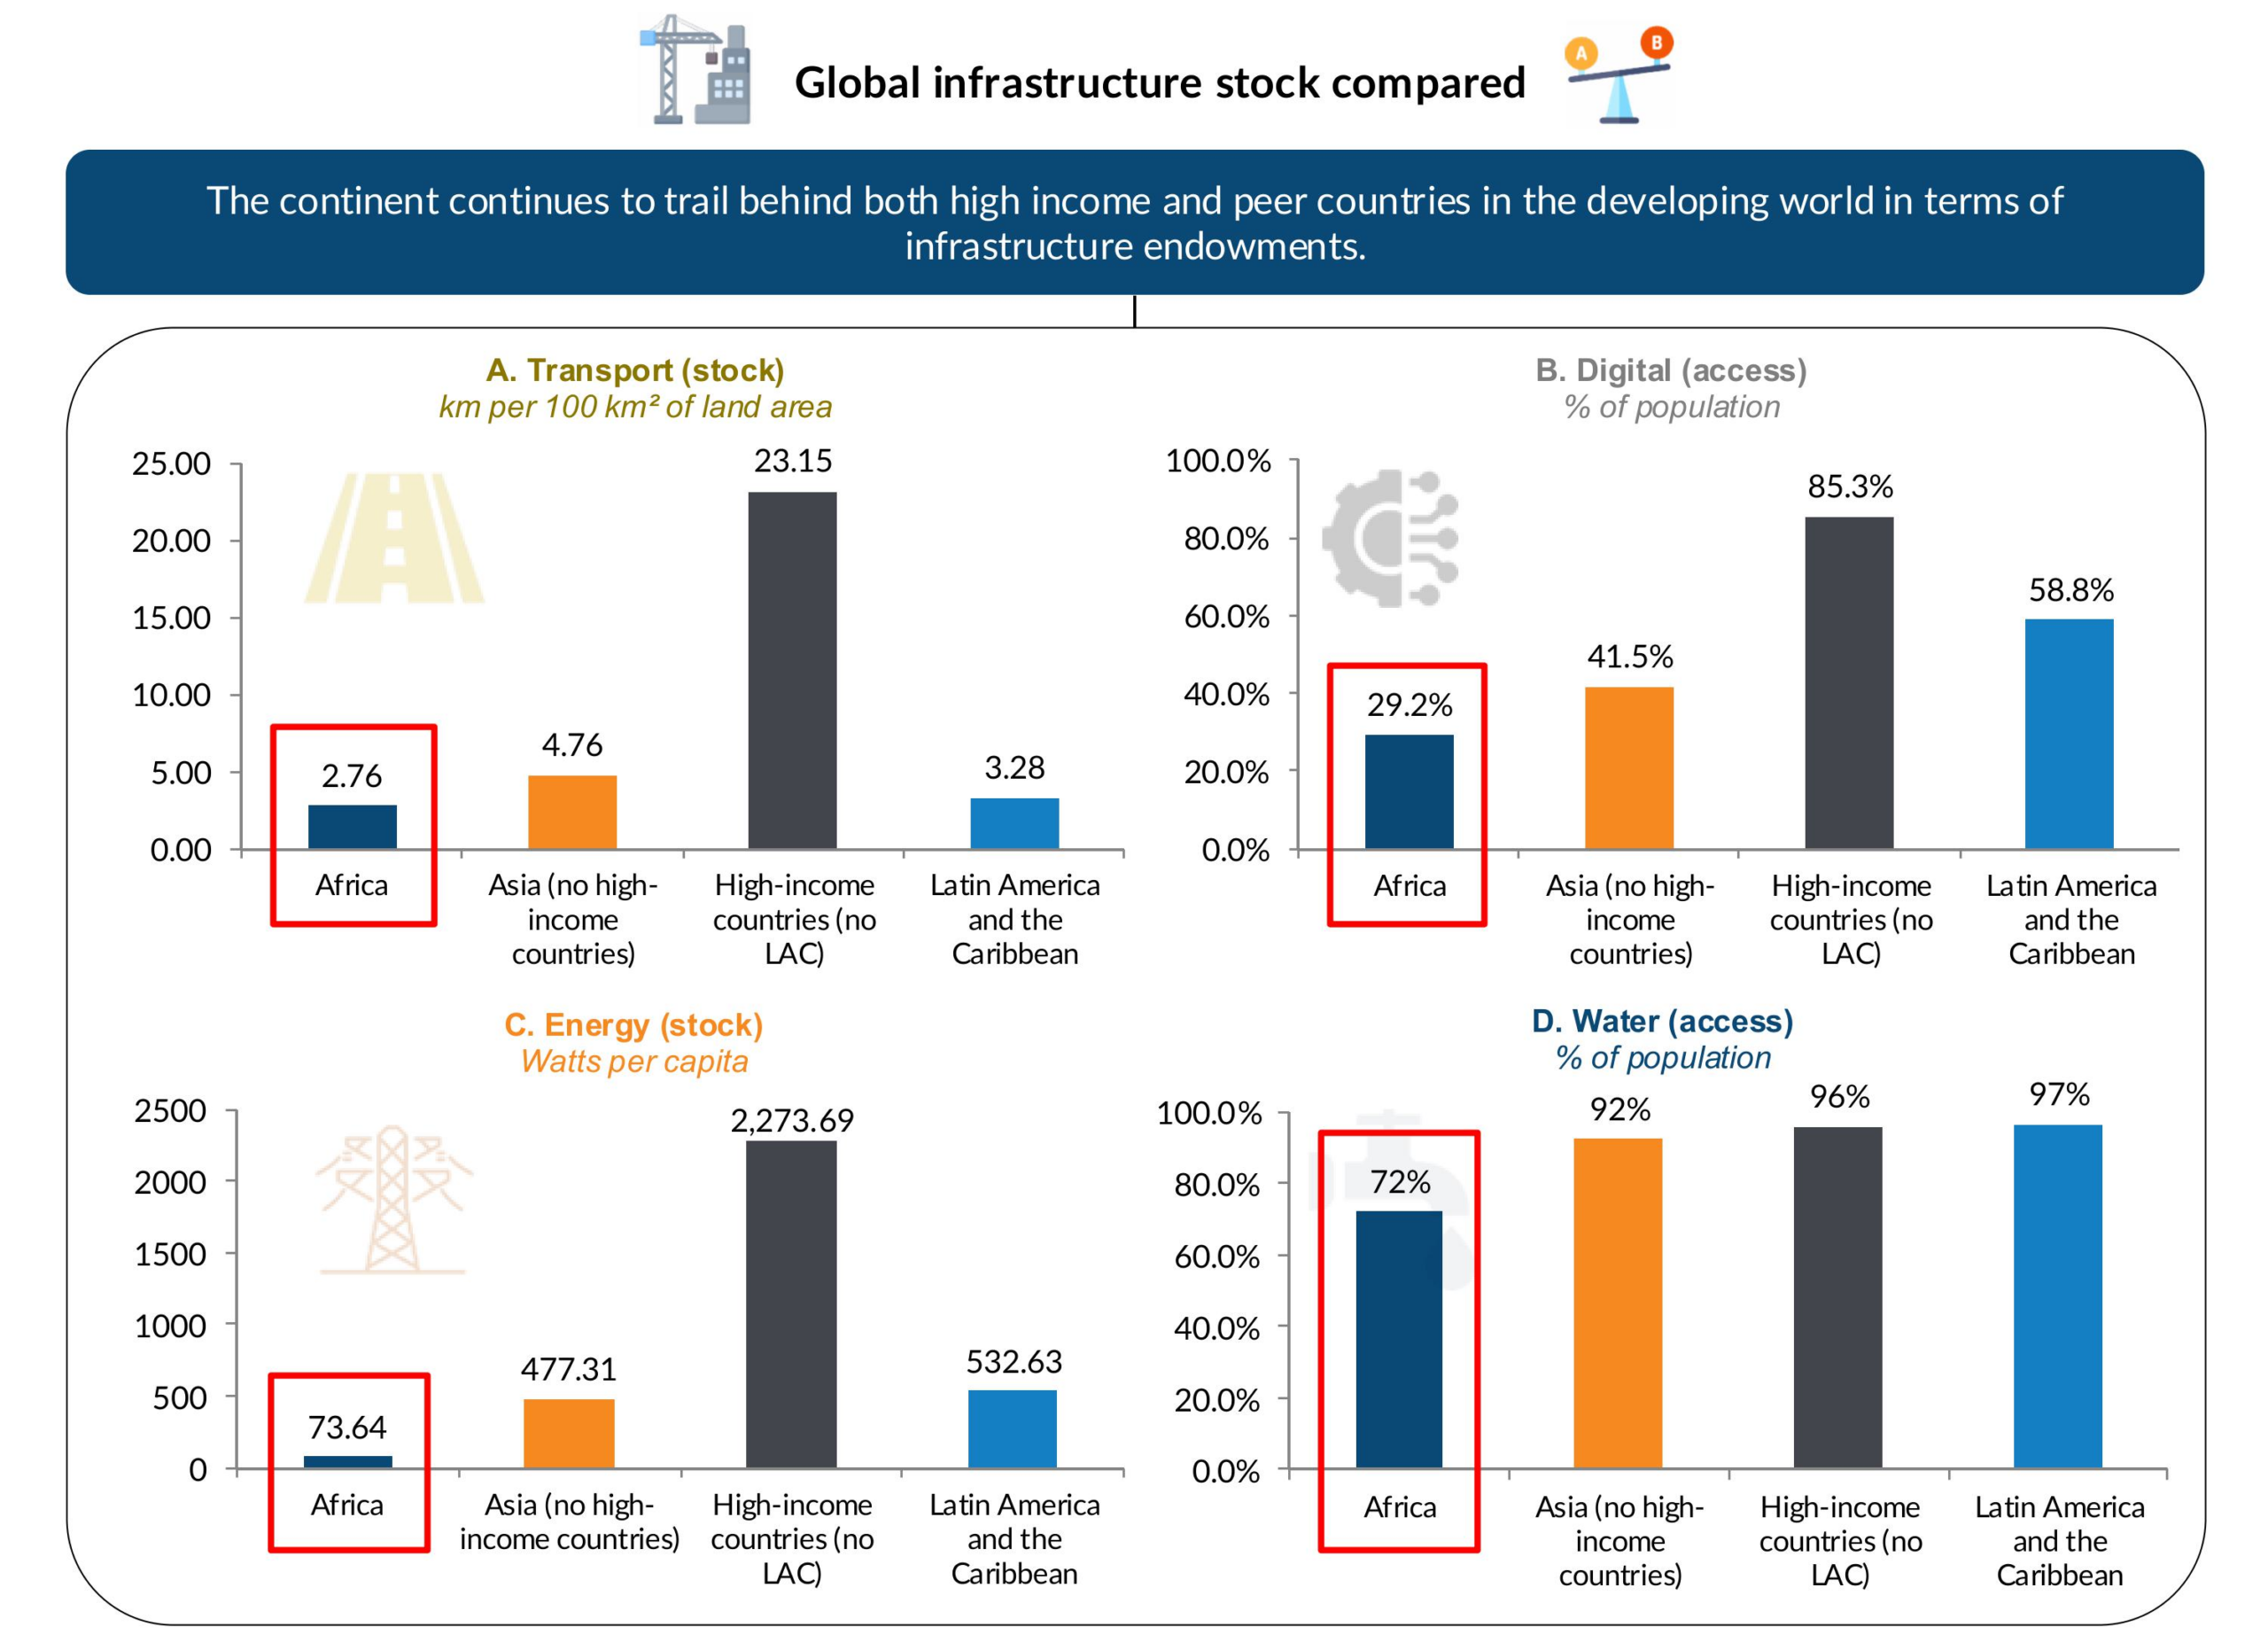
The 2 March 2026 Strait of Hormuz closure forced Maersk, CMA CGM, and Hapag-Lloyd to reroute vessels via the Cape of Good Hope—testing Africa’s port resilience. With $155 billion in annual infrastructure investment needed through 2040, African nations are shifting from raw-material export logistics to value-added manufacturing and multimodal redundancy. Roads (32%) and railways (24%) lead spending, while 42% funds maintenance. Regional integration under AfCFTA and diversified PPPs strengthen routing alternatives amid Red Sea and Hormuz disruptions—offering global supply chains new levers for geopolitical risk mitigation.
According to www.inonafrica.com, the closure of the Strait of Hormuz on 2 March 2026 catalysed a strategic pivot in African port infrastructure investment—from capacity expansion to supply chain resilience.
Africa’s Infrastructure Shift Amid Global Disruption
The Hormuz shutdown triggered immediate rerouting by global carriers including Maersk, CMA CGM, and Hapag-Lloyd, diverting vessels around the Cape of Good Hope. This surge in maritime traffic placed unprecedented demand on African seaports—testing their ability to absorb volume spikes without congestion or delay. The crisis followed earlier stress tests: since October 2023, repeated disruptions to the Suez Canal by Yemen-based militants had already forced reroutes through African waters, affecting shipments bound for African markets—including consumer goods and industrial products.
From Raw-Export to Value-Added Logistics
African infrastructure upgrades are no longer solely about moving raw materials to export terminals. Investment is now focused on enabling local transformation—e.g., processing rare earth elements into electric vehicle batteries or refining crude oil domestically. This shift supports industrialisation goals under the African Union’s Agenda 2063 and aims to capture higher value from Africa’s natural resources.
Investment Scale and Priorities
- Roads account for 32% of total transportation infrastructure investment; railways for 24%
- 42% of spending goes toward maintenance of existing infrastructure
- The OECD estimates US$155 billion in average annual investment through 2040 is needed to bring African transport systems to parity with Asia, Europe, and North America
- Such investment could lift average annual GDP growth to 4.5% by 2040—doubling current growth and advancing Agenda 2063’s 7% target
Resilience Through Diversification and Integration
African governments are reducing overreliance on single foreign partners—for instance, moving beyond China-led construction or Germany-supplied rail hardware—by expanding public-private partnerships (PPPs). Regional integration is accelerating: national road and rail networks now interconnect as part of the continental African highway system. This enables redundancy—if one corridor is disrupted by storms or conflict, shippers access alternative routes. The AfCFTA further amplifies this benefit by boosting intra-African trade and reinforcing multimodal connectivity across ports, airports, and river shipping systems.
Practitioner Implications for Global Supply Chains
For supply chain professionals, Africa’s infrastructure evolution signals more than regional development—it presents tangible options for supply chain diversification and geopolitical risk mitigation. Ports like Maputo (Mozambique) have prioritised operational efficiency and responsiveness, while others—such as Mombasa (Kenya)—still face bottlenecks that undermine resilience. As rerouting becomes recurrent—not exceptional—shippers must assess not just port depth or container throughput, but also hinterland connectivity, customs digitisation, warehousing readiness, and real-time visibility across integrated rail, road, and air cargo nodes. Maintenance discipline and PPP governance quality now carry equal weight with headline infrastructure metrics in supplier risk scoring.
Source: www.inonafrica.com
Compiled from international media by the SCI.AI editorial team.
Done reading? Ask SCI.AI your follow-up questions
Answers grounded in our tariff knowledge graph and in-house reporting. Guests: 3 questions/day — free accounts: 30/week.


