Maersk's transformation from ocean carrier to digital logistics integrator: 700+ vessels, 17% of global container trade, and a platform strategy reshaping supply chain intermediaries.
From Ocean Carrier to Integrated Logistics Orchestrator
For over a century, A.P. Møller–Mærsk (Maersk) defined itself by the rhythmic pulse of container ships cutting across maritime trade lanes—steel hulls laden with standardized steel boxes, moving goods from port to port along predictable, linear routes. That identity, however, has undergone a deliberate and irreversible metamorphosis. According to AlphaTechFinance’s report “Maersk Goes Fully Digital,” Maersk has executed a strategic pivot—not merely an incremental upgrade—away from its historical role as a pure ocean carrier toward becoming a digital end-to-end logistics integrator. This transition, formally initiated in 2016, represents one of the most consequential structural reconfigurations in modern supply chain history.
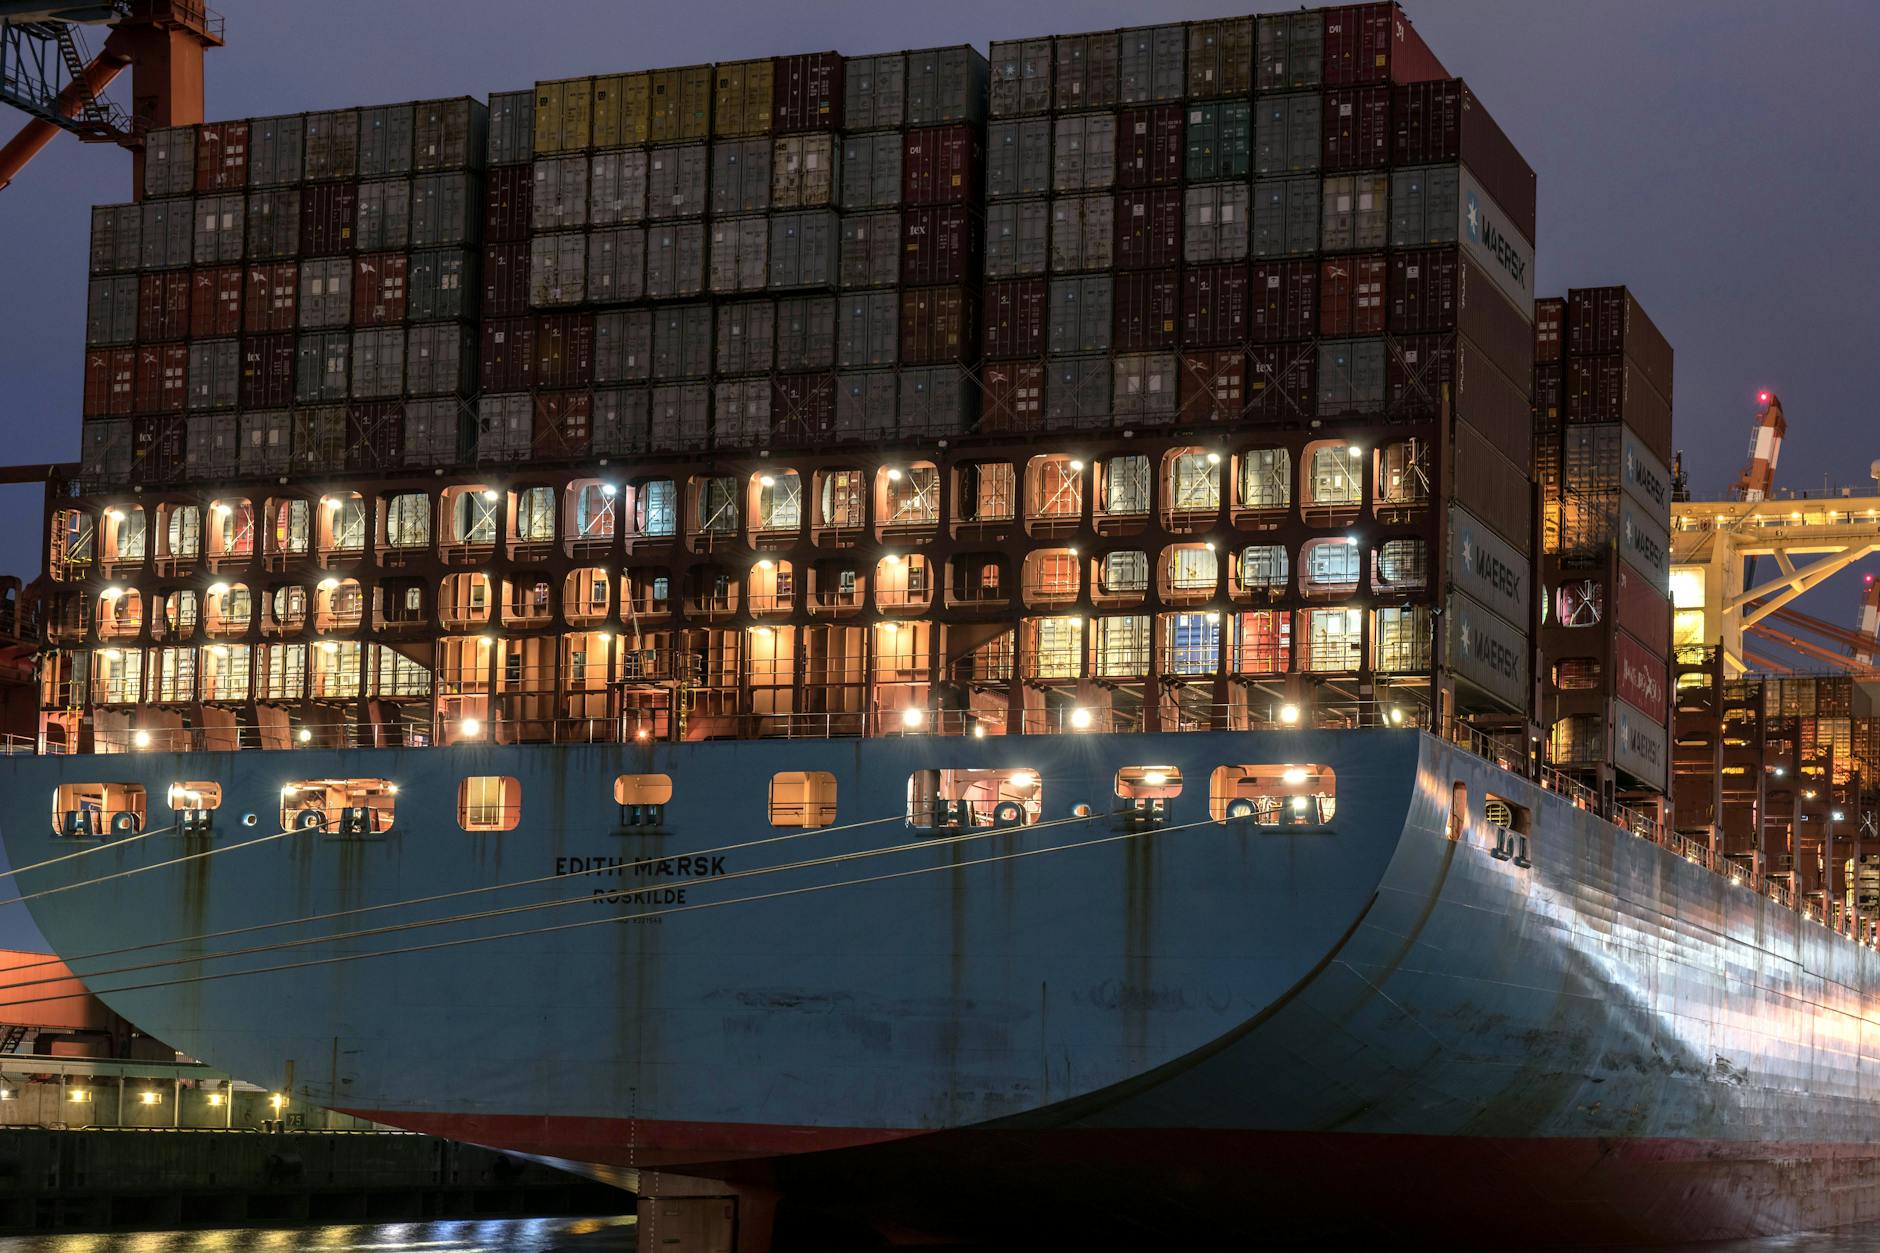
The scale of Maersk’s physical infrastructure remains formidable: 700+ vessels operating across 130+ countries, handling approximately 17% of global container trade. Yet these figures now serve not as endpoints but as foundational nodes within a far more expansive and interconnected architecture. The company no longer measures success solely by vessel utilization or port call efficiency; instead, it evaluates performance through data velocity, API integration depth, digital documentation adoption rates, and the percentage of revenue derived from integrated logistics solutions. As AlphaTechFinance underscores, this is not digitization *of* shipping—it is digitization *as* shipping’s successor logic. The ocean leg is now just one module in a modular, API-driven service stack that begins with supplier onboarding and ends with last-mile delivery confirmation—each layer instrumented, automated, and interoperable. This shift reflects a deeper industry truth: global trade is no longer constrained by nautical miles, but by data latency, document friction, and fragmented visibility across disparate systems. Maersk’s ambition is to collapse those constraints—not by building bigger ships, but by building smarter, unified digital rails.
Strategic Acquisitions: Building the Integrated Stack Through Vertical Integration
Maersk’s transformation did not unfold in isolation or through organic growth alone. Rather, it was accelerated and systematized via a disciplined series of acquisitions—each selected to fill critical capability gaps in its evolving end-to-end value proposition. AlphaTechFinance identifies six pivotal acquisitions: Hamburg Sud, Damco, Performance Team, Senator International, Visible SCM, and Pilot Freight Services. Each acquisition served a distinct architectural purpose in constructing a vertically integrated logistics platform.
Hamburg Sud, acquired in 2017, expanded Maersk’s vessel capacity and strengthened its presence in South America—a region previously underserved in its network. Damco, acquired in 2019, brought deep expertise in customs brokerage, freight forwarding, and inland transportation, effectively bridging the gap between ocean carriage and landside execution. Performance Team (acquired 2021) added specialized contract logistics and warehousing capabilities in North America, while Senator International (2022) delivered European road and rail freight networks, enhancing cross-border land connectivity. Visible SCM contributed advanced supply chain visibility technology—including real-time event tracking, predictive alerts, and multi-tier supplier mapping—enabling Maersk to offer actionable intelligence beyond mere location updates. Finally, Pilot Freight Services (2023) fortified last-mile delivery and final-mile logistics in the U.S., completing the physical continuum from origin warehouse to consignee doorstep.
Critically, these were not standalone bolt-ons. Per AlphaTechFinance, Maersk systematically integrated each acquisition into its unified digital platform—standardizing processes, migrating legacy systems, and enforcing API-first design principles across the combined entity. The result is a single customer interface capable of orchestrating ocean, air, rail, road, warehousing, customs clearance, and trade finance—all under one contractual and technological umbrella. This level of vertical integration is unprecedented among legacy carriers and positions Maersk not as a competitor to third-party logistics providers (3PLs), but as a hybrid entity that combines carrier scale with 3PL agility and digital-native architecture.
The Digital Platform: Beyond Tracking to Transactional Autonomy
At the heart of Maersk’s new operating model lies its proprietary digital platform—an ecosystem that transcends conventional shipment tracking dashboards. As documented by AlphaTechFinance, this platform delivers five core functional pillars: instant booking, real-time shipment tracking, fully digital documentation (including electronic bills of lading—eBL), seamless API connectivity, and embedded trade finance and insurance services. Crucially, these are not isolated features but interdependent layers designed for transactional autonomy.
Instant booking eliminates manual email exchanges, phone calls, and PDF-based rate inquiries. Customers input origin, destination, cargo type, and timeline—and receive binding, real-time pricing and space confirmation within seconds. Real-time shipment tracking extends beyond GPS coordinates; it integrates port terminal data, customs clearance status, weather disruptions, and labor action alerts to generate predictive ETAs with quantified confidence intervals. Digital documentation—particularly the eBL—is transformative: it replaces paper-based bills of lading, which historically caused delays averaging 5–7 days per shipment due to courier transit, bank endorsements, and physical presentation requirements. With eBL, title transfer occurs digitally in minutes, reducing documentary lead time by over 90%.
API connectivity enables enterprise-grade integration. Global shippers embed Maersk’s logistics services directly into their ERP (e.g., SAP S/4HANA), TMS (e.g., Manhattan SCALE), and procurement platforms—triggering bookings, updating inventory records, and reconciling invoices automatically. Embedded trade finance and insurance represent perhaps the most sophisticated layer: customers can access working capital loans, letters of credit, and cargo insurance at the point of booking—powered by real-time shipment data and risk scoring algorithms. This convergence of logistics and finance dissolves traditional silos, turning movement of goods into a synchronized financial and physical event. As AlphaTechFinance notes, this platform isn’t merely “digital”—it is *transactional infrastructure*, where logistics decisions trigger immediate financial and operational consequences without human intervention.
Financial Resilience and Revenue Diversification Amid Volatility
The volatility inherent in global shipping markets underscores the strategic necessity of Maersk’s diversification. AlphaTechFinance highlights a stark reality: shipping rates can swing by 400–500%—a magnitude of fluctuation that renders pure carrier business models inherently unstable. In 2022, Maersk achieved peak financial performance—$54B+ in revenue and $30B+ in EBIT—largely driven by extraordinary rate surges during pandemic-related supply chain congestion. Yet that peak also exposed vulnerability: such windfall revenues were unsustainable and unrepeatable under normalized market conditions.
Maersk’s response was structural, not cyclical. Its Logistics & Services revenue target—50% of total group revenue—reflects a deliberate de-risking strategy. Unlike ocean freight, which is highly sensitive to macroeconomic cycles, fuel prices, and geopolitical shocks, integrated logistics services generate recurring, contracted revenue streams. Warehousing contracts, managed transportation agreements, and digital platform subscription fees exhibit significantly lower volatility. Moreover, these services carry higher margins: while ocean carriage operates on razor-thin margins under competitive pressure, value-added logistics—especially data-enabled visibility, customs optimization, and embedded finance—command premium pricing based on outcomes, not just capacity.
This financial recalibration is further reinforced by Maersk’s scale and workforce: ~100,000 employees globally provide the operational muscle to deliver complex, multi-modal solutions consistently. Their collective expertise—spanning customs law, multimodal routing algorithms, trade compliance, and cloud infrastructure management—constitutes a defensible moat. AlphaTechFinance emphasizes that Maersk’s digital transformation is not cost-cutting theater; it is revenue architecture redesign. By shifting half its income to less volatile, higher-margin, digitally enabled services, Maersk insulates itself against the very volatility that once defined its industry—and transforms uncertainty into a competitive advantage.
Sustainability as Systemic Infrastructure, Not Peripheral Initiative
Sustainability at Maersk is neither a marketing add-on nor a regulatory concession—it is hardwired into the technical and financial foundations of its digital transformation. AlphaTechFinance reports Maersk’s commitment to net-zero emissions by 2040, backed by concrete capital allocation: 25 methanol-powered containerships have been ordered. These vessels are not experimental prototypes; they are commercially viable, large-scale assets designed for transoceanic deployment. Their propulsion choice—green methanol—was selected precisely because it leverages existing port infrastructure (unlike hydrogen or ammonia) and enables drop-in fuel use without engine modification, accelerating adoption timelines.
However, Maersk’s sustainability architecture extends far beyond vessel propulsion. Its digital platform is itself a decarbonization tool. Instant booking and dynamic routing algorithms reduce empty container repositioning—the single largest source of avoidable emissions in liner shipping. Digital documentation eliminates paper production, printing, and global courier emissions. Real-time visibility allows shippers to consolidate shipments, optimize load factors, and avoid expedited air freight as a panic response to delayed information. Furthermore, Maersk’s API ecosystem enables customers to integrate carbon accounting modules directly into their logistics workflows—automatically calculating Scope 3 emissions per shipment and feeding data into corporate ESG reporting systems.
This systemic approach reflects a fundamental insight articulated in AlphaTechFinance’s analysis: decarbonization cannot be outsourced to shipyards or fuel suppliers alone. It must be engineered into the decision-making fabric of global trade. When a procurement manager books a shipment via Maersk’s platform, the interface displays not only cost and transit time—but also carbon intensity, fuel type, and alignment with the buyer’s science-based targets. Sustainability becomes a parameter in the optimization function, not a post-hoc audit. That integration—where environmental impact is treated as a first-class data variable alongside cost, speed, and reliability—is what distinguishes Maersk’s net-zero strategy from aspirational pledges.
Implications for the Broader Supply Chain Ecosystem
Maersk’s evolution carries profound implications for every actor in the global supply chain—from multinational manufacturers to SME exporters, from port authorities to software vendors. First, it establishes a new benchmark for interoperability. As Maersk mandates API-first integration across its acquisitions and platform, it compels ecosystem partners—terminal operators, customs agencies, trucking firms—to modernize their own digital interfaces. Legacy EDI systems are being replaced by RESTful APIs and standardized data schemas (e.g., DCSA’s eBL standards), raising the baseline for all participants.
Second, it reshapes power dynamics. Historically, shippers negotiated separately with ocean carriers, forwarders, customs brokers, and insurers—each holding partial visibility and leverage. Maersk’s integrated offering consolidates authority, enabling single-point accountability and simplified contracting. For smaller enterprises, this reduces complexity and entry barriers to global trade. For larger corporations, it introduces strategic tension: do they deepen reliance on a single, increasingly dominant integrator—or invest heavily in building proprietary orchestration platforms? Both paths demand significant capital and talent.
Third, it accelerates industry-wide digitization. Competitors—including MSC, CMA CGM, and Hapag-Lloyd—are responding with parallel digital initiatives, yet none match Maersk’s scope of vertical integration or platform maturity. This competitive pressure is driving faster adoption of eBL, real-time visibility, and embedded finance across the sector. Regulatory bodies, notably the EU and Singapore, are aligning legal frameworks to recognize digital trade documents—validating Maersk’s early bets.
Finally, Maersk’s trajectory signals a broader paradigm shift: the future of supply chains belongs not to the largest vessel owner, but to the most capable data integrator. As AlphaTechFinance observes, Maersk’s 700 vessels remain essential—but they are now managed, optimized, and monetized through a digital layer that is infinitely more scalable, defensible, and valuable. In an era where supply chain resilience is measured in milliseconds of data latency and certainty of document validity, Maersk has not just upgraded its fleet—it has rewritten the operating system of global trade.
Source: AlphaTechFinance
This article was AI-assisted and reviewed by our editorial team.