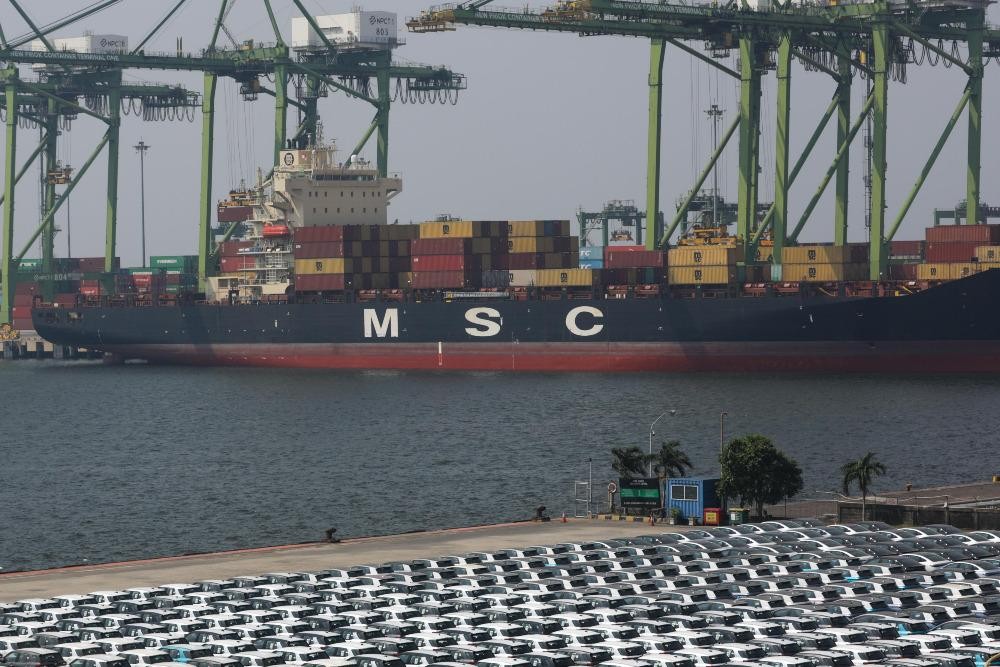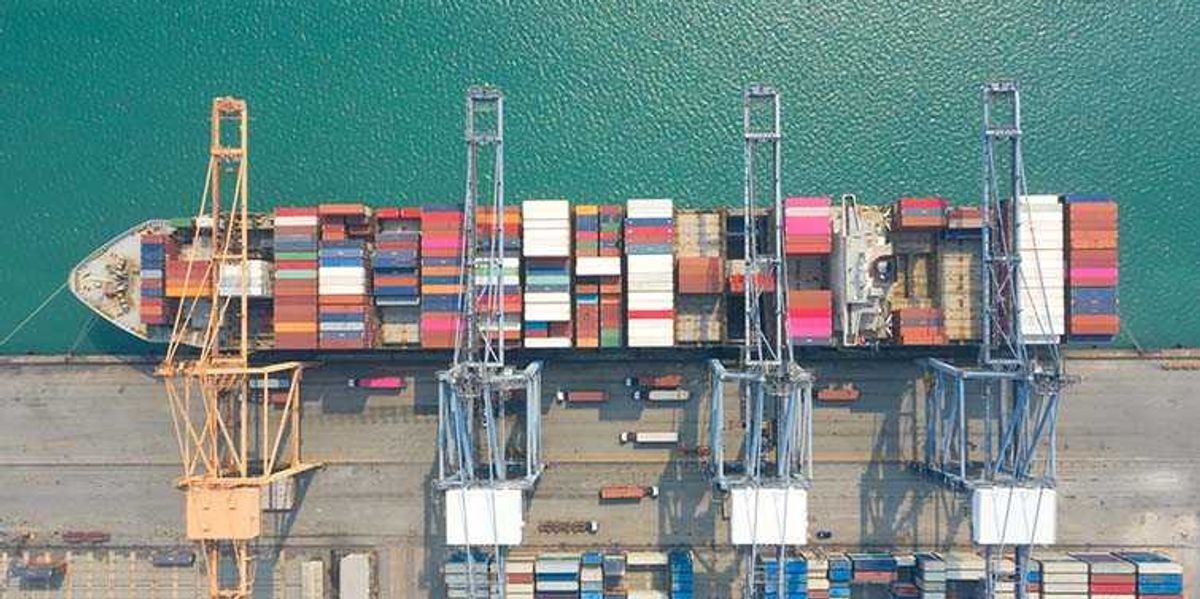
Ocean freight rates are rising sharply amid an early peak shipping season, with transpacific rates to the U.S. West Coast up 19% to over $5,700/FEU and transatlantic rates to the U.S. East Coast up 13% to $7,400/FEU. Shippers are frontloading orders ahead of July manufacturer price hikes, Section 301 tariff introductions, and fuel surcharge increases. Freightos and C.H. Robinson both confirm the market has tightened faster than expected, with Mike Short of C.H. Robinson noting shippers are now competing not just for space but for 'the right sailing.' Geopolitical constraints — including delayed normalization of Strait of Hormuz traffic — and port congestion further compress effective capacity.
According to www.thescxchange.com, ocean freight rates have surged amid an unusually early peak shipping season, driven by shippers frontloading orders ahead of fuel surcharges, tariff changes, and manufacturer price hikes.
Early Peak Season Accelerates Rate Inflation
Industry analysts attribute the sharp upward pressure on container shipping costs to a confluence of demand-side triggers occurring weeks earlier than typical. Freightos identified three primary catalysts: impending increases in bunker adjustment factors (BAFs), the expiration of Section 122 tariffs and introduction of new Section 301 tariffs for transpacific shipments, and scheduled July manufacturer price hikes. These developments have prompted widespread order acceleration — a phenomenon known as frontloading — across global supply chains.
This structural shift has already reshaped market dynamics. Transpacific spot rates to the U.S. West Coast rose 19% to more than $5,700 per FEU (forty-foot equivalent unit), while transatlantic rates to the U.S. East Coast climbed 13% to $7,400/FEU. Notably, current spot rates have already surpassed last year’s peak season highs — a benchmark typically reached only in late August or September.
Capacity Constraints Amplify Pricing Pressure
Despite continued growth in the global container ship fleet, effective capacity remains constrained. Freightos explained that elevated starting rates — adjusted for fuel costs — combined with persistent Red Sea diversions and port congestion are collectively reducing available sailing slots and delaying vessel turnarounds. These delays effectively shrink usable capacity, intensifying competition for space and pushing spot prices to “very elevated levels”.
The situation is further complicated by seasonal bottlenecks. Peak season congestion at major ports — particularly those handling transpacific cargo — is causing cascading schedule disruptions. Vessels arriving late miss their planned berthing windows, triggering domino effects across the network. According to Freightos, this operational friction compounds demand-driven rate hikes rather than offsetting them.
C.H. Robinson Confirms Market Tightening
Freight broker C.H. Robinson corroborated the accelerated timeline and tightening conditions. In a company release, Mike Short, president of global forwarding at C.H. Robinson, stated:
“We’re seeing booking activity pull forward across Trans-Pacific lanes as shippers position inventory earlier and react to expected cost increases. Peak season has effectively started early, and it’s shrinking the window to secure preferred departures. Shippers aren’t just competing for space right now, they’re competing for the right sailing.”
The firm characterized the current environment as one where market deterioration is likely to continue before any stabilization occurs. This outlook reflects growing consensus among logistics providers that the early peak season will persist through at least June 2026 and potentially into Q3 2026.
Geopolitical and Regulatory Headwinds Mount
Compounding these commercial pressures are ongoing geopolitical disruptions. Although fuel costs have eased slightly due to sporadic progress on reopening ship traffic through the Strait of Hormuz, full normalization remains distant. Experts estimate cargo flow through the Strait will not return to pre-disruption levels for at least three months, according to analysis cited in the source article.
Simultaneously, regulatory uncertainty looms large. The pending expiration of Section 122 tariffs — which currently provide temporary relief for certain imports — and the simultaneous implementation of new Section 301 duties create a dual-edged incentive for shippers to move goods before July 2026. This regulatory calendar, coupled with manufacturer-level price adjustments slated for the same month, forms a synchronized trigger point for near-term freight acceleration.
Source: thescxchange.com
Compiled from international media by the SCI.AI editorial team.