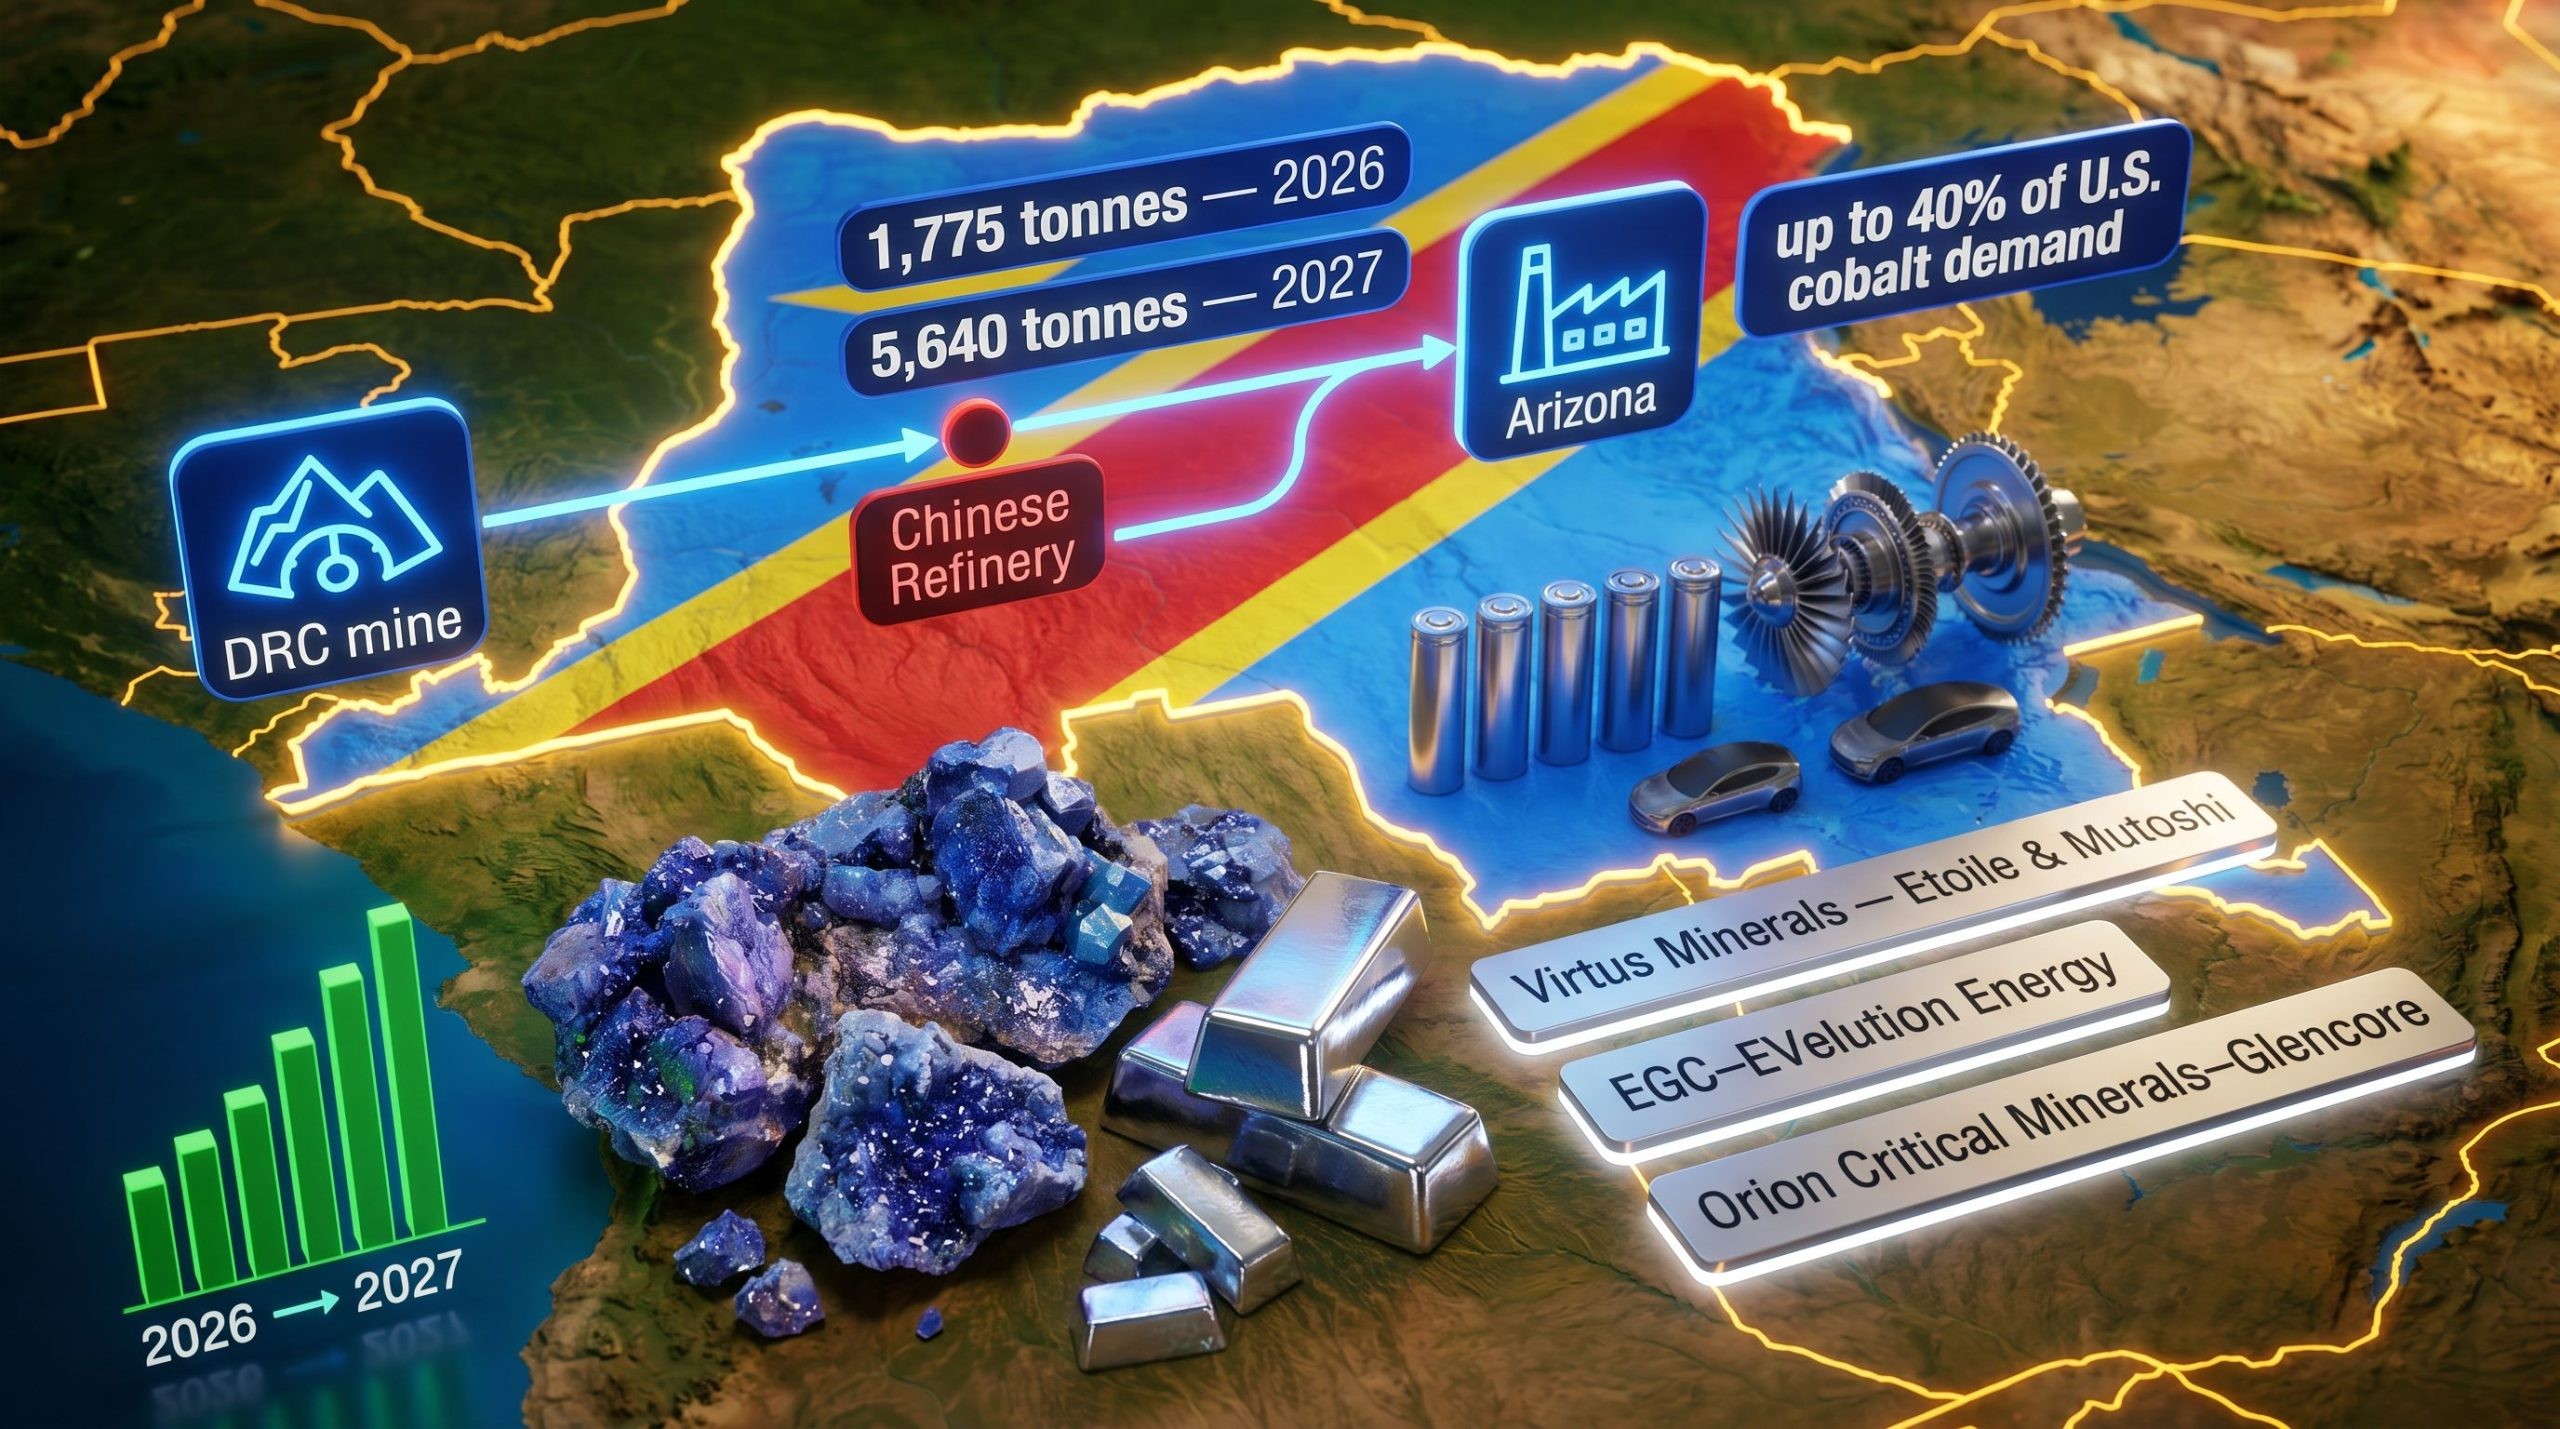
The U.S. and Democratic Republic of Congo have formalised a bilateral mining partnership to establish the first direct cobalt supply pipeline, following the DRC’s 2025 export embargo and growing U.S. reliance on Chinese-refined material. In 2024, the DRC produced 73% of global cobalt but supplied zero direct imports to the U.S. — while Norway, Finland, Canada, and Japan supplied 70% of U.S. cobalt imports, mostly as refining intermediaries. U.S. domestic cobalt mining stood at just 300 tonnes in 2025. On 13 May 2026, state-owned EGC began negotiations with U.S. firm EVelution Energy. The U.S. imported 1,103 tonnes of cobalt in February 2025 — the final month before the DRC’s embargo took full effect.
According to discoveryalert.com.au, the United States and the Democratic Republic of Congo have formalised a bilateral mining partnership — culminating in active negotiations to establish the first direct cobalt supply pipeline from Kinshasa to U.S. battery and defence manufacturers. This marks a structural shift away from decades of indirect procurement through Chinese refineries.
The Refining Chokepoint: Why Geography of Processing Trumps Mining Origin
For cobalt — a metal critical to NMC lithium-ion batteries, jet engine superalloys, and defence-grade cutting tools — control over refining infrastructure has long been more decisive than control over mines. As the source states, the DRC accounted for 73% of global cobalt production in 2024, yet it did not appear among named U.S. cobalt import sources in either 2024 or 2025. Instead, Norway, Finland, Canada, and Japan supplied approximately 70% of U.S. cobalt imports during those years — functioning primarily as refining intermediaries rather than primary producers. Only Canada operates meaningful domestic mining capacity alongside refining. This arrangement meant U.S. manufacturers were consuming Congolese cobalt indirectly, embedded in Chinese-refined products routed through European hubs.
National Security Imperative: The Domestic Shortfall and Import Architecture
The strategic vulnerability is quantified by U.S. Geological Survey (USGS) data: only 300 tonnes of cobalt were mined domestically in the United States in 2025. That volume represents less than 0.5% of annual U.S. industrial and defence demand. With no viable near-term path to close this gap via domestic mining, import architecture has become a primary national security concern — not a secondary trade issue. The USGS further confirms that the DRC remained conspicuously absent from U.S. import manifests even in 2023, when other African suppliers such as Zambia, Morocco, and Madagascar appeared in granular breakdowns. This absence reflects China’s dominant refining footprint: over 80% of global cobalt refining capacity is concentrated in China, much of it fed by long-term upstream investments in Congolese mining assets.
The 2025 Embargo: Catalyst for Direct Engagement
A pivotal inflection point came with the DRC’s cobalt export ban in early 2025. Deployed as a sovereign instrument to assert pricing control and compel direct engagement, the embargo triggered an immediate U.S. response. According to Congolese mining statistics, the United States imported 1,103 tonnes of cobalt in February 2025 — during the narrow window before the embargo took full effect. This single-month figure demonstrated both urgent U.S. demand and acute exposure to policy shifts in Kinshasa. The suspension was later replaced by a quota-based export system, paving the way for the December 2025 formalisation of the U.S.–DRC bilateral mining partnership — the legal foundation for current direct-sourcing initiatives.
EGC and EVelution Energy: Building the First Direct Pipeline
Under that framework, concrete action followed. On 13 May 2026, Entreprise Générale du Cobalt (EGC), the DRC’s state-owned cobalt entity established in 2019, announced it was in active negotiations with U.S.-based EVelution Energy to establish a direct cobalt supply relationship. EGC holds a legal monopoly over artisanal cobalt purchasing and export coordination in the DRC, giving it central authority in structuring transparent, traceable flows. This initiative targets refined cobalt metal, cobalt sulfate, and cobalt hydroxide — all key inputs for cathode manufacturing and defence applications. Unlike prior arrangements, shipments will be tracked from mine site to U.S. port with verified chain-of-custody documentation, addressing longstanding concerns over human rights compliance and origin transparency.
Supply Chain Implications for Practitioners
For supply chain professionals, the shift carries tangible operational consequences. First, sourcing teams must now engage directly with sovereign mineral entities — requiring new expertise in public-sector contracting, sovereign risk assessment, and multi-stakeholder due diligence (including artisanal mining cooperatives). Second, logistics planning must accommodate new maritime routes: DRC cobalt exports currently transit through Dar es Salaam (Tanzania) or Durban (South Africa), adding 10–14 days to ocean lead times versus Chinese-origin material. Third, quality assurance protocols must be adapted to handle intermediate cobalt hydroxide shipments — which require onboarding of new assay labs certified to ASTM E2917-21 standards. Finally, the U.S. Department of Commerce’s newly launched Critical Minerals Sourcing Portal (launched Q1 2026) now mandates real-time reporting of cobalt origin verification for all Tier 1 automotive and defence contractors — effective July 2026.
Source: discoveryalert.com.au
Compiled from international media by the SCI.AI editorial team.