Skip to content

Japan & Korea Supply Chain

Japan Approves $4B for Rapidus Chip Development

According to asia.nikkei.com, Japan has approved an additional $4 billion in support for Rapidus to secure domestic advanced semiconductor capacity. The move comes amid a global memory chip shortage projected to last until 2027—and possibly through 2030—driven by AI demand and production ramp constraints. Supply chain professionals face cascading pressures: rising chip costs (e.g., Sony’s $100 PS5 price hike), material shortages (helium, lasers, PCBs), and geopolitical rerouting (e.g., Chinese chip tool imports via Singapore/Malaysia). Regional responses include South Korea’s front-loading, Taiwan’s helium reserve calls, and TSMC’s warning on Middle East gas price impacts. These developments underscore systemic interdependencies and urgent resilience planning needs.

Original source: asia.nikkei.com

Japan Approves $4B for Rapidus Chip Development

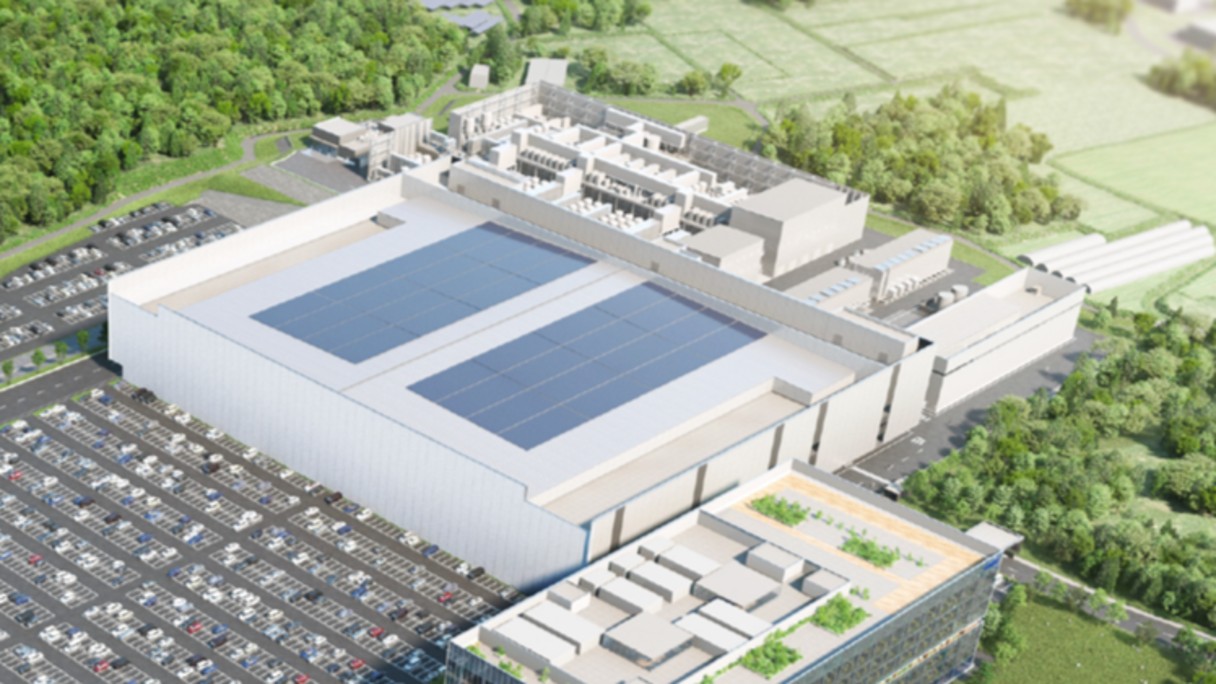
According to asia.nikkei.com, Japan has approved an additional $4 billion in government support for Rapidus, its domestic advanced semiconductor initiative aimed at ensuring stable supplies of cutting-edge chips. The funding is part of a broader national strategy to bolster economic security and reduce reliance on foreign manufacturing capabilities, particularly amid intensifying geopolitical pressures and supply chain vulnerabilities.

Rapidus and Japan’s Semiconductor Sovereignty Push

The announcement—dated 11 April 2026—follows earlier Japanese investments in semiconductor infrastructure and reflects mounting urgency to establish domestic 2-nm and sub-2-nm chip production. Rapidus, established in 2022 with backing from major Japanese corporations including Sony, Toyota, NEC, and NTT, is tasked with developing next-generation logic chips for AI and high-performance computing. Fujitsu plans to develop 1.4-nm chips for AI processing, with production outsourced to Rapidus, as reported on 31 March 2026.

Global Memory Shortage Extends Through 2027

Meanwhile, the global memory chip shortage remains acute. According to the source, the shortage is set to last until 2027, driven by sustained demand from AI data centers and constrained ramp-up timelines—even as Samsung, SK Hynix, and Micron increase output. SK Hynix separately stated the broader global memory chip crunch could extend until 2030. This prolonged scarcity directly impacts downstream industries: Sony announced it will hike PlayStation 5 prices in the U.S. by $100, citing surging memory chip costs—the second such increase in less than a year (28 March 2026).

Supply Chain Shifts and Geopolitical Pressures

Geopolitical risk is accelerating regional reconfiguration. Chinese firms are bypassing U.S. export controls by importing U.S.-made chip tools via Singapore and Malaysia, where imports hit record levels (15 April 2026). South Korean exporters are front-loading semiconductor purchases due to Iran war–related helium supply concerns (1 April 2026), while Taiwan’s chip industry is urgently calling for helium and LNG reserves—and for the first time voicing support for nuclear power—as Middle East conflict risks escalate (8 April 2026). TSMC warned that higher gas prices from the Middle East conflict could impact profitability and emphasized there are ‘no shortcuts’ for Tesla’s Terafab project (16 April 2026).

Industry-Wide Material and Component Constraints

Beyond chips, shortages are spreading across supporting technologies. Japan’s glassmakers Asahi Kasei and AGC are retooling to produce high-end substrates and glass cloth for AI chips (2 April 2026). Laser, PCB, component, and materials shortages are now emerging across the tech sector (1 April 2026). The Hormuz Strait closure risk is described as ‘quietly threatening’ Taiwan’s semiconductor industry, with implications spanning AI data centers to automobiles (1 April 2026).

Source: Nikkei Asia

Compiled from international media by the SCI.AI editorial team.
Ask SCI.AI Finished reading? Continue with SCI.AI. Explore the related policy, route, company and historical context. Continue asking
South Korea, Brazil Ink Deal to Restart Mercosur FTA Talks
Japan & Korea Supply Chain

South Korea, Brazil Ink Deal to Restart Mercosur FTA Talks

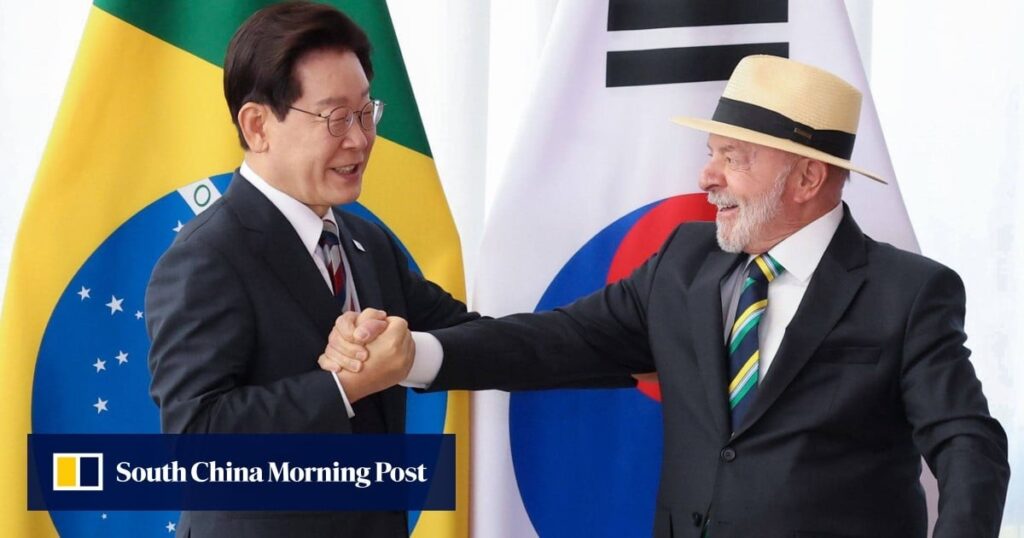
South Korean President Lee Jae Myung and Brazilian President Luiz Inacio Lula da Silva agreed on 29 July 2026 to restart free-trade negotiations with Mercosur — the South American bloc of Argentina, Brazil, Paraguay, Uruguay, and Bolivia. A joint working group will prepare a formal declaration for the Mercosur summit in December 2026. Talks, launched in 2018, stalled in late 2021 amid manufacturing-sector concerns. Analysts say Seoul must back diplomacy with real investment and technology transfer. Mercosur’s $3.5 trillion GDP and 270 million consumers make it a high-stakes opportunity for Korean exporters and supply chain planners.

Nissan to export US-built Murano to Japan in early 2027
Japan & Korea Supply Chain

Nissan to export US-built Murano to Japan in early 2027

Nissan will begin exporting the U.S.-built Murano SUV from its Smyrna, Tennessee plant to Japan in early 2027 — enabled by a September 2025 U.S.-Japan trade agreement that lowered U.S. tariffs on Japanese vehicles from 25% to 15% and allowed U.S. safety certification to satisfy Japanese regulatory requirements. The move follows similar announcements by Toyota and Honda to export U.S.-assembled models to Japan. Nissan sold 42,747 Muranos in the U.S. in 2025 (+121% YoY), while U.S. imports from Japan fell 17.4% to 113,094 units.

Japan pulls rare earths from Pacific seabed; yttrium at 1,000 ppm
Japan & Korea Supply Chain

Japan pulls rare earths from Pacific seabed; yttrium at 1,000 ppm

Japan has extracted yttrium (at 1,000 ppm) and dysprosium from deep-sea mud near Minamitorishima Island in the Pacific Ocean. The seabed deposit lies 2,000 meters below the surface and forms part of Japan’s strategy to cut reliance on China, which supplies over 90% of global refined rare earths. Despite promising assays, commercialization remains distant due to high extraction costs, with no large-scale pilot expected before the late 2030s. Japan has committed ¥15 billion to seabed R&D and is pursuing alternatives including domestic smelting (Shin-Etsu, 2027), recycling (Toyota Tsusho), and international partnerships (France, Greenland). Rare-earth costs for Japanese firms rose over 20% in early 2026.

Welcome Back!

Login to your account below

Create New Account!

Fill the forms below to register

Retrieve your password

Please enter your username or email address to reset your password.

Scan to share via WeChat

Open WeChat and scan the QR code to share

QR Code

Add New Playlist